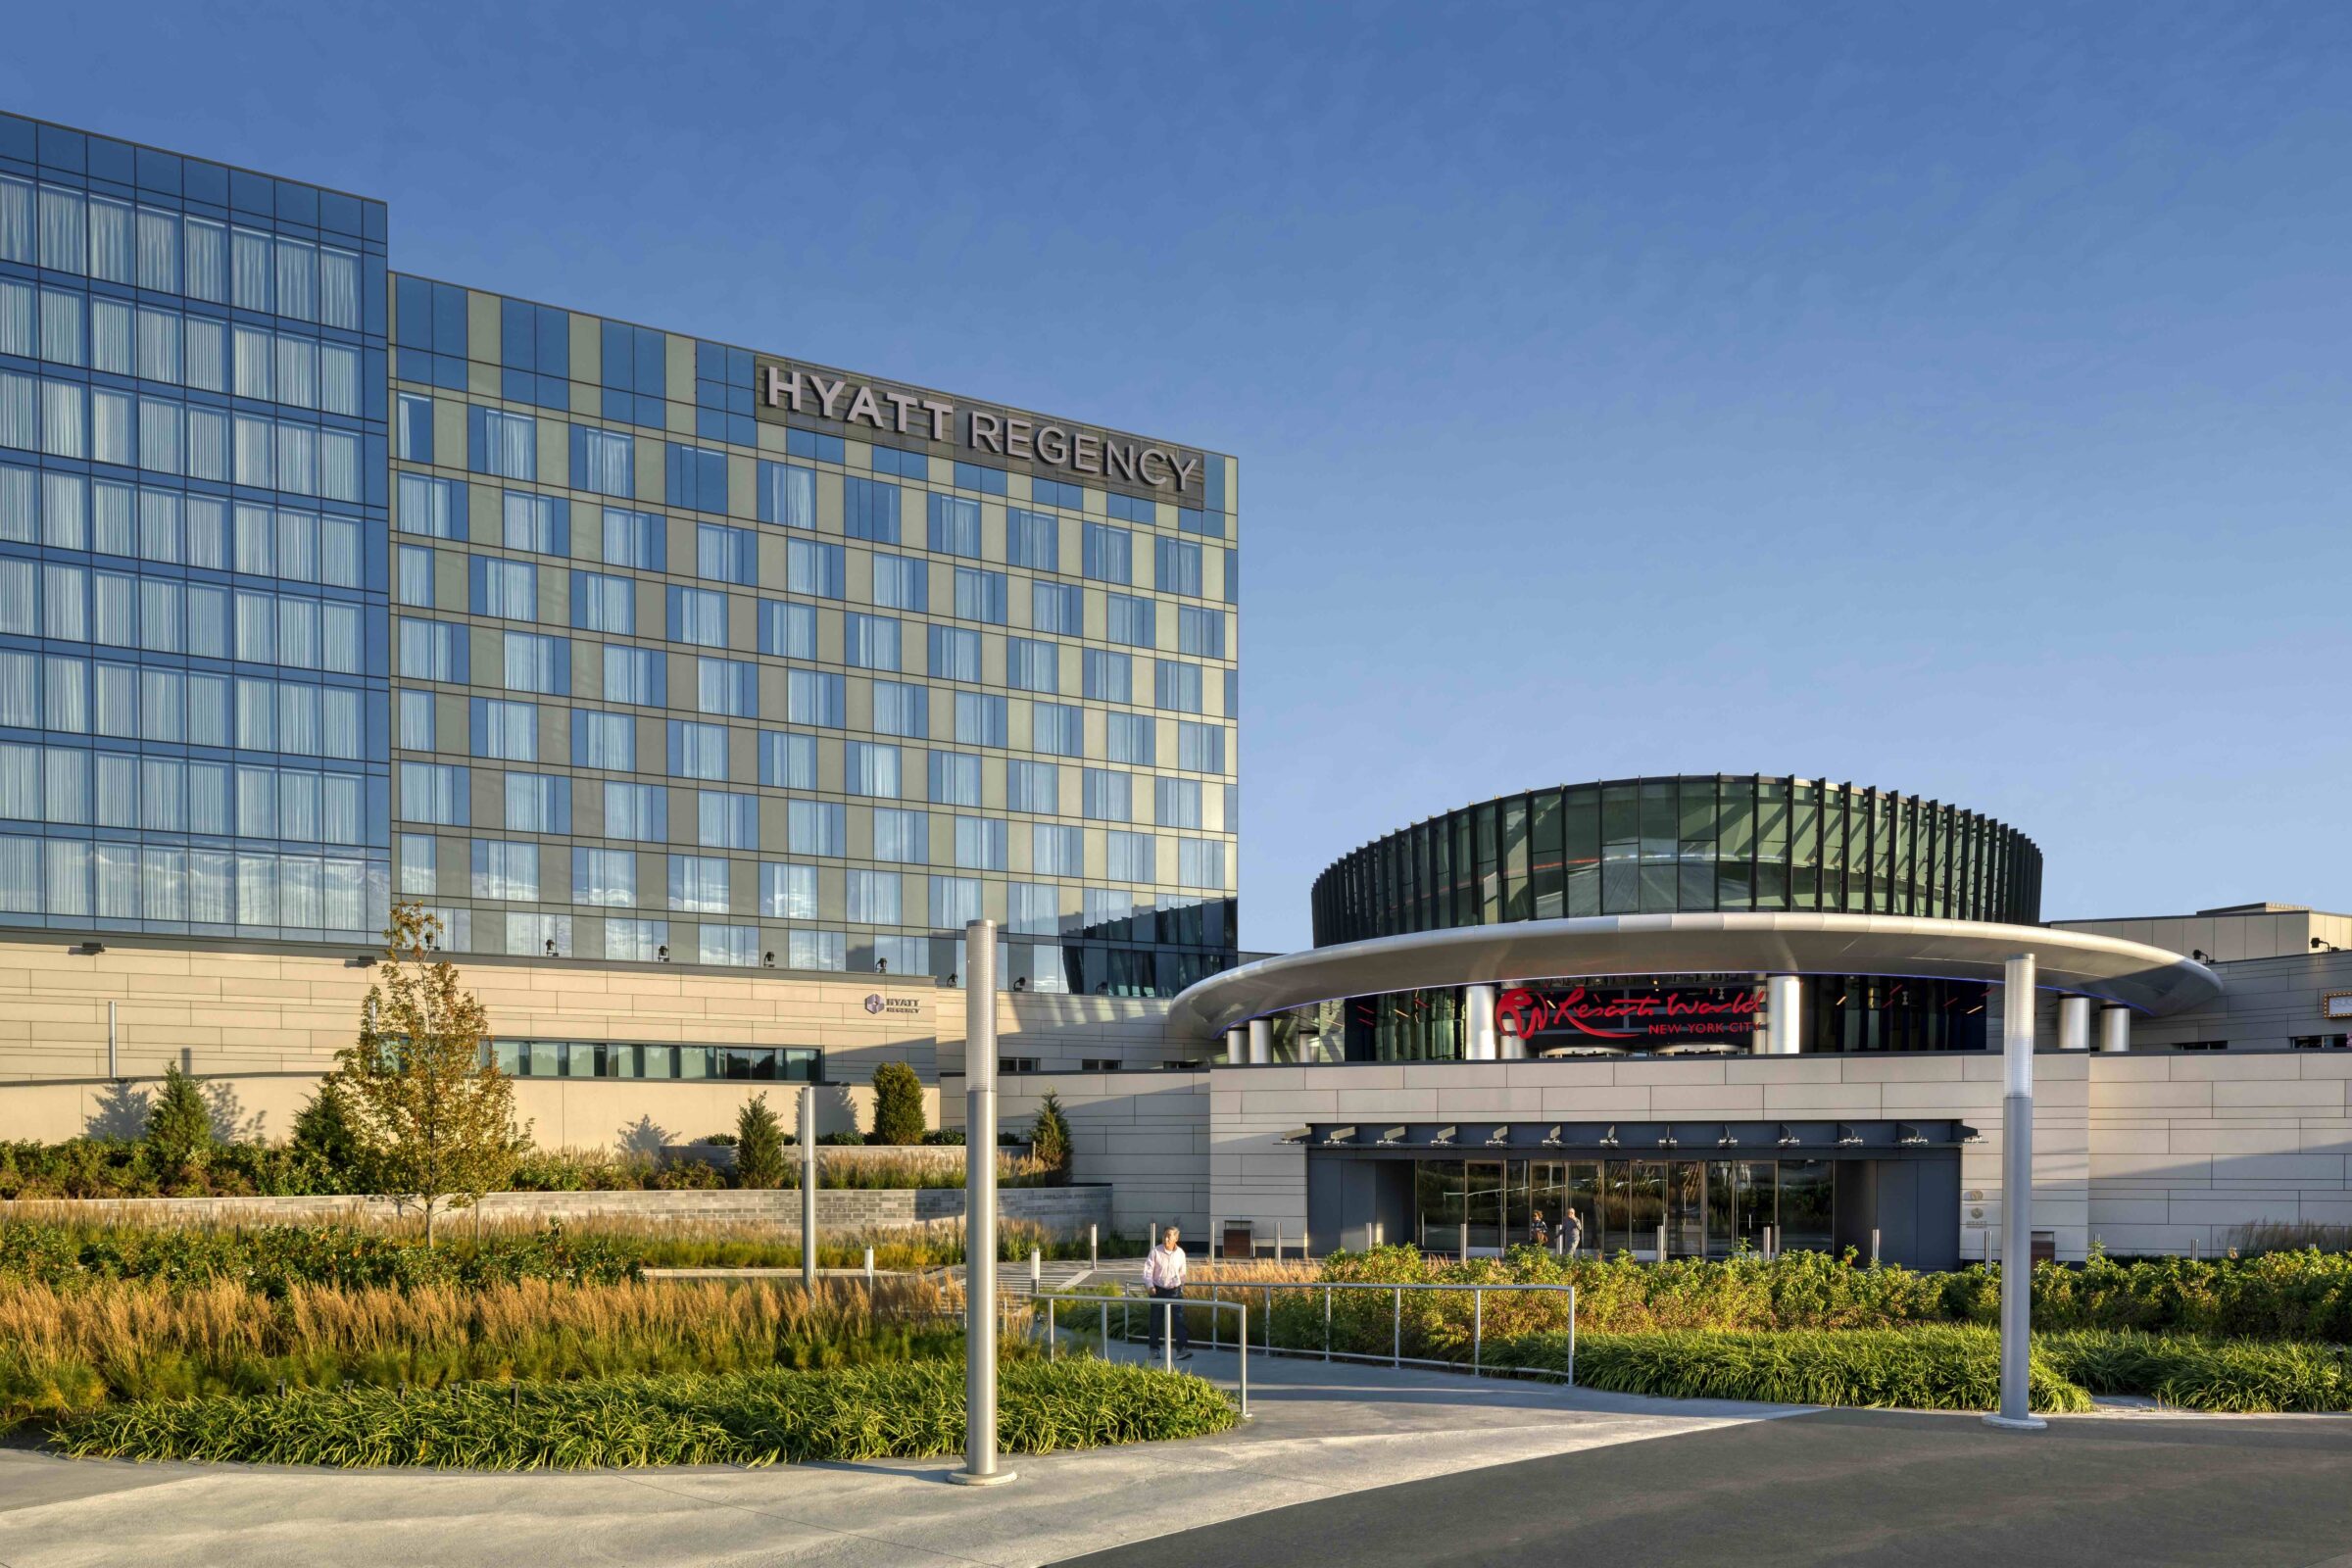

Costs related to the launch of full casino operations at Resorts World New York City (RWNYC) in April saw Genting Malaysia report a narrowed profit of MYR27.0 million (US$6.7 million) in the three months to 30 June 2026, down from MYR398.1 million (US$98.4 million) a year earlier.
However, it also saw revenue soar. While Genting Malaysia did not break down its US revenue by property, the company’s US and Bahamas segment reported a 166% year-on-year increase in revenue to MYR1.53 billion (US$378 million) – helping group-wide revenue rise 32% to MYR3.85 billion (US$952 million). This was despite Resorts World Genting (RWG) in Malaysia seeing a slight 1% decline in revenue to MYR1.77 billion (US$438 million) and the UK and Egypt also seeing a 1% fall to MYR506.2 million (US$125 million).
Group-wide Adjusted EBITDA was down 18% year-on-year to MYR844 million (US$209 million) although this reflected RWNYC opening costs as well as the recognition of a Forex loss compared with a substantial gain in 2Q25.
In a note, Nomura analysts observed that US-segment revenue was up 121% compared with the March 2026 quarter, with Adjusted EBITDA up 169%.
RWNYC launched downstate New York’s first casino table games on 28 April, offering 242 table games and 2,500 slot machines, before adding another 1,400 slot machines last month. It also broke ground on the next phase of the US$5.5 billion RWNYC expansion in late July.
At RWG, revenue of MYR1.77 billion (US$438 million), while down year-on-year, was 6% higher quarter-on-quarter with Adjusted EBITDA up 20% sequentially to MYR615 million (US$214 million) thanks in part to a higher VIP win rate.
In a note, Nomura’s Tushar Mohata and Alpa Aggarwal said they consider the Malaysia results to be a “positive surprise, given the disruptions caused by the war in the Middle East to flights and tourist arrivals.”
In its earnings release, Genting Malaysia said, “The global economic environment remains uncertain, as renewed geopolitical tensions in the Middle East and macroeconomic risks continue weighing on the growth outlook. Against this backdrop, the Group remains cautious of the near-term prospects in Malaysia and continues to monitor the operating environment closely in order to navigate these near-term headwinds.”
It added, “For Malaysia, regional and domestic tourism are expected to remain under pressure as higher airfares and travel-related fuel costs continue to weigh on consumer travel decisions. The Group is focused on operational discipline and yield management to optimise performance and manage costs, whilst continuing to enhance RWG’s integrated resort offerings to drive visitation and customer engagement. The Group continues to invest selectively in infrastructure, attractions and new experiences to broaden its offerings and strengthen its competitiveness.”
RelatedPosts