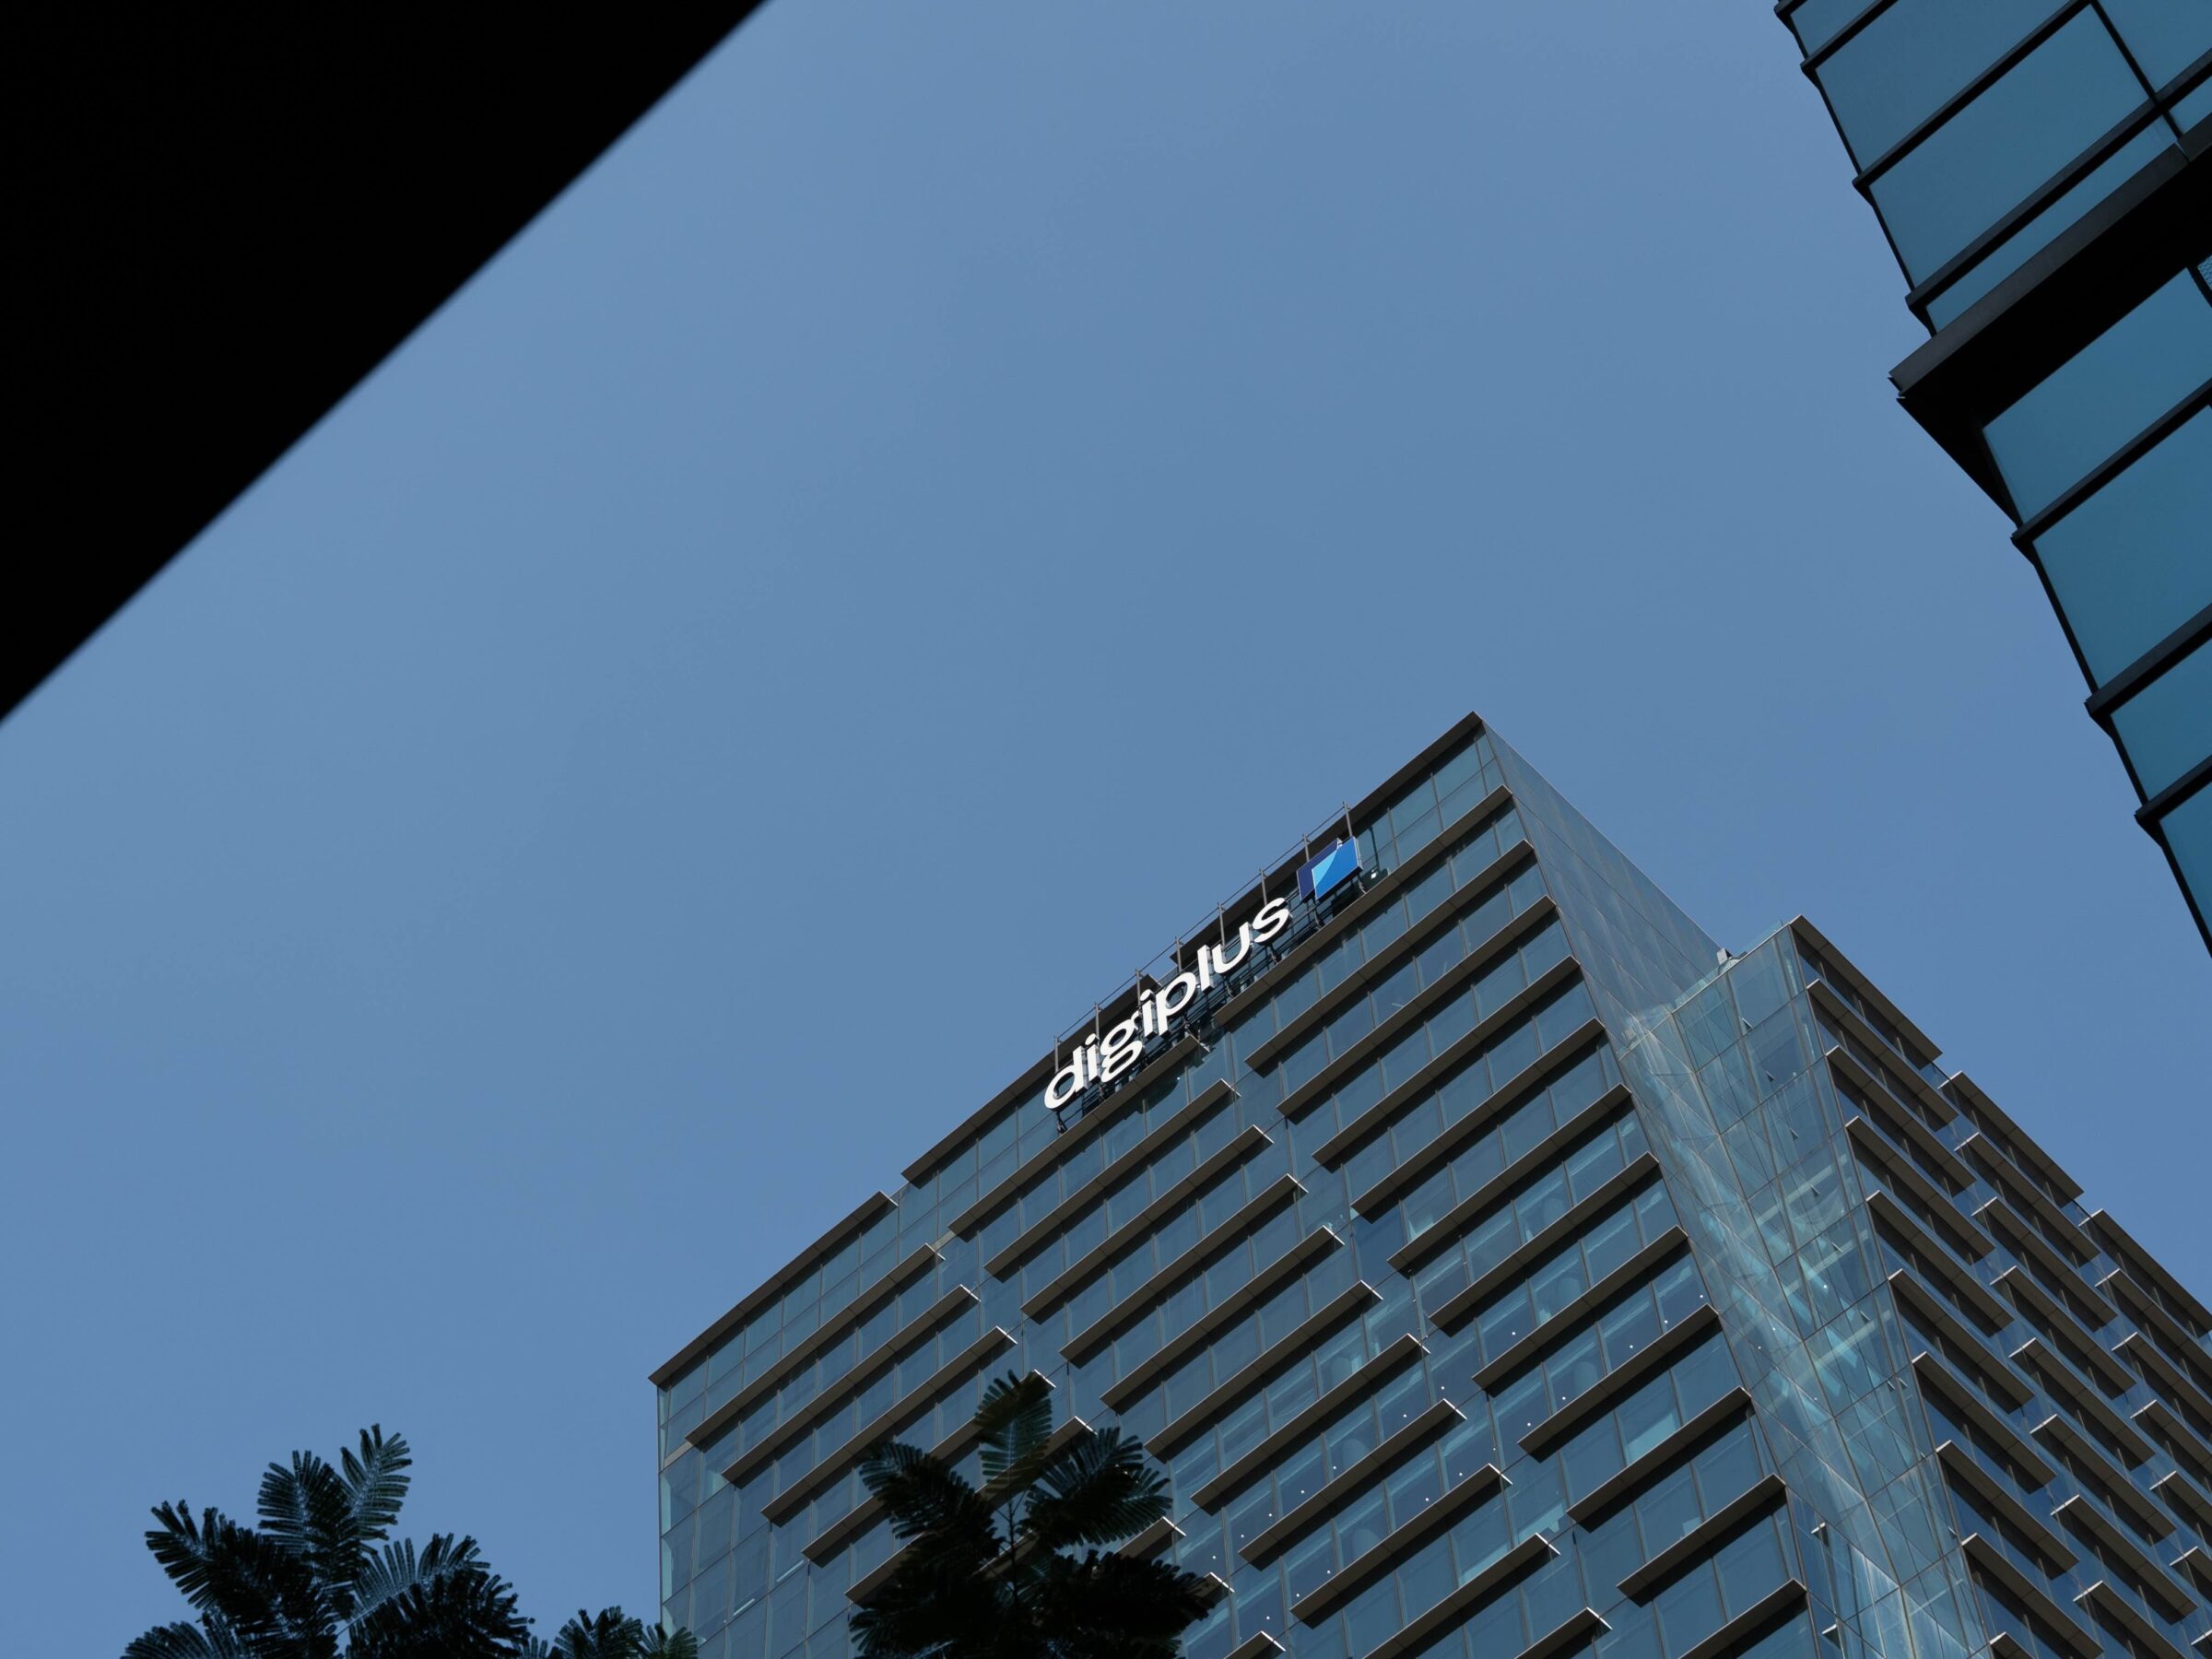

DigiPlus Interactive Corp, the Philippines’ leading online gaming operator with an estimated market share of 38.5%, is well-positioned to emerge from anticipated industry consolidation unscathed at a time when tightening regulations on the sector are causing earnings volatility, according to ratings agency Moody’s.
These ongoing regulatory changes will favor incumbents such as DigiPlus, Moody’s added, noting that the company has the meaningful scale, financial resources and the ability to adapt.
The comments from the ratings agency formed part of a Thursday note in which it assigned DigiPlus a first-time B1 corporate family rating with a stable outlook.
Yu Sheng Tay, a Moody’s Ratings Assistant Vice President, explained, “DigiPlus’ B1 rating reflects its leadership in the Philippines’ online gaming market and strong financial profile, underpinned by low leverage, robust cash generation and a net cash position.
“These strengths are balanced by exposure to regulatory change and intense competition in the Philippines’ online gaming sector. DigiPlus’ growth ambitions in land-based casinos and overseas markets also introduce execution risk.”
Moody’s said it expects DigiPlus’s EBITDA to decline to about Php11.4 billion (US$182 million) in 2026 from Php14.3 billion (US$228 million) last year, reflecting the central bank’s 2025 directive requiring mobile wallet and payment providers to delink in-app access to online gaming platforms. Weaker consumer sentiment amid high fuel prices and broader inflationary pressures have also constrained discretionary gaming spending.
EBITDA is, however, expected to recover to between Php14 billion and Php15 billion (US$223 million and US$334 million) )in 2027 and 2028, supported by organic growth and contributions from the company’s investment into International Entertainment Corp – the parent company of Manila’s LaVie Resort & Casino.
Moody’s observed that the IEC investment via convertible notes, which could see DigiPlus assume a controlling 53.89% stake in IEC, is “driven partly by a more favorable hybrid gaming tax structure” although it would also increase its exposure to IEC’s capital commitments through 2033 related to LaVie.
While the increasingly competitive environment in the Philippines’ online sector present another risk going forward – with its reliance on third party game providers limiting product differentiation – Moody’s said the company’s existing position in the market gives it a huge advantage over rivals.
“[Digiplus’s] portfolio of more than 1,000 games across bingo, electronic games and sports betting supports user engagement, network effects and efficient customer acquisition and retention,” the ratings agency stated.
“The company also benefits from favorable industry and demographic trends as the Philippines shifts toward a more regulated online gaming framework. A young and growing population, rising urbanization and an expanding middle-income segment underpin long-term demand for online gaming, while regulatory efforts to curb illegal gambling and strengthen oversight support the growth of licensed operators.”
Amid all of this, Moody’s said the credit metrics of DigiPlus remain strong, with strong free cash flow and leverage that is likely to remain below 0.5x for the next 12 to 18 months pending any significant acquisitions.
It noted that the company’s B1 rating takes into account continued regulatory tightening, but not the outright ban on online gaming that some senators have called for.
RelatedPosts