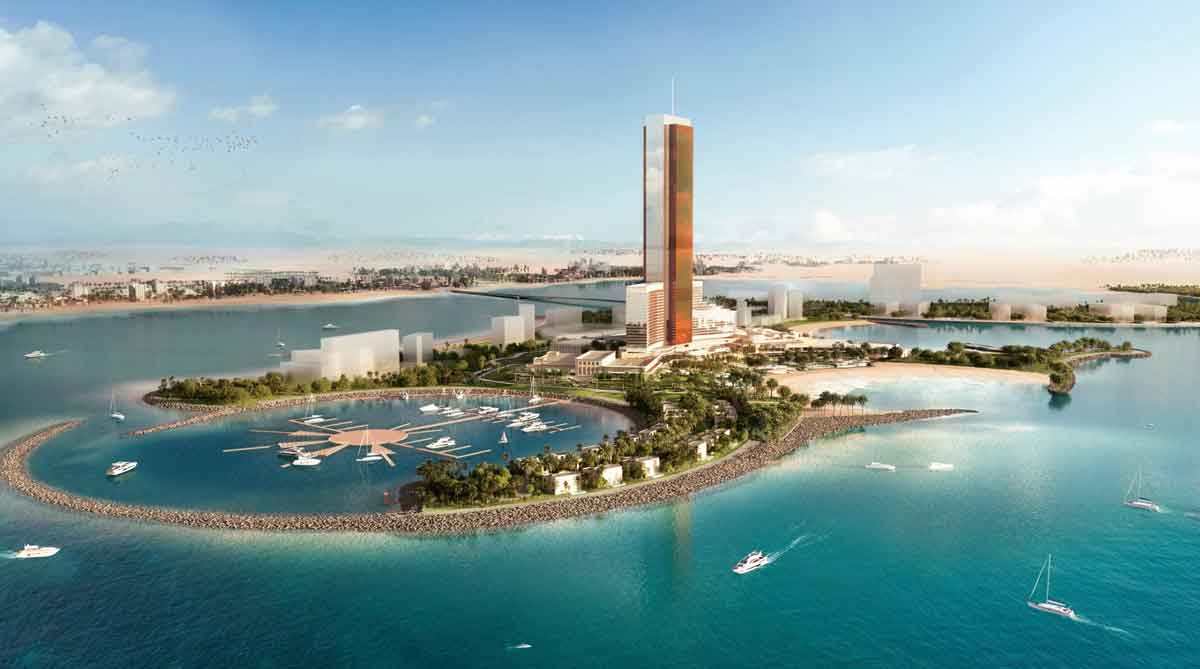

Wynn’s US$5.7 billion UAE integrated resort project, Wynn Al Marjan Island, could beat its own GGR projections according to analysis from independent sell-side research firm Wolfe Research, citing parallels to the hugely successful Singapore casino market.
In a recent note, Wolfe Research analyst Peter Supino suggested investors are massively undervaluing Wynn Resorts stocks, which are down around 37% sine the start of the year. While there remains some risk to near-term Macau estimates – where Wynn operates two integrated resorts – Supino believes Wynn shares could soar by as much as 60% from current levels by the end of 2027 given the huge potential of Wynn Al Marjan Island to exceed already high expectations.
“In building the first integrated resort-casino in the Middle East, Wynn brings its global luxury brand positioning to a UAE market brimming with demand for super premium consumption, tourism and untold vices,” he wrote.
“According to [real estate firm] Knight Frank, 43% of the UAE’s upcoming hotel room supply through 2030 is classified as luxury. One-third of the world’s population lives within a 4-hour flight of the UAE.
“Benchmarking against Singapore, another wealthy limited license casino market popular with tourists, suggests Wynn’s Al Marjan could beat the UAE GGR targets it laid out in December 2025.”
In a December 2025 investor presentation, Wynn Resorts forecast that gaming revenues at Wynn Al Marjan Island could reach up to US$1.66 billion annually with Adjusted Property EBITDA of between US$390 million and US$570 million annually once Wynn’s management fees are taken into account.
RelatedPosts