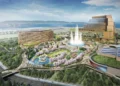


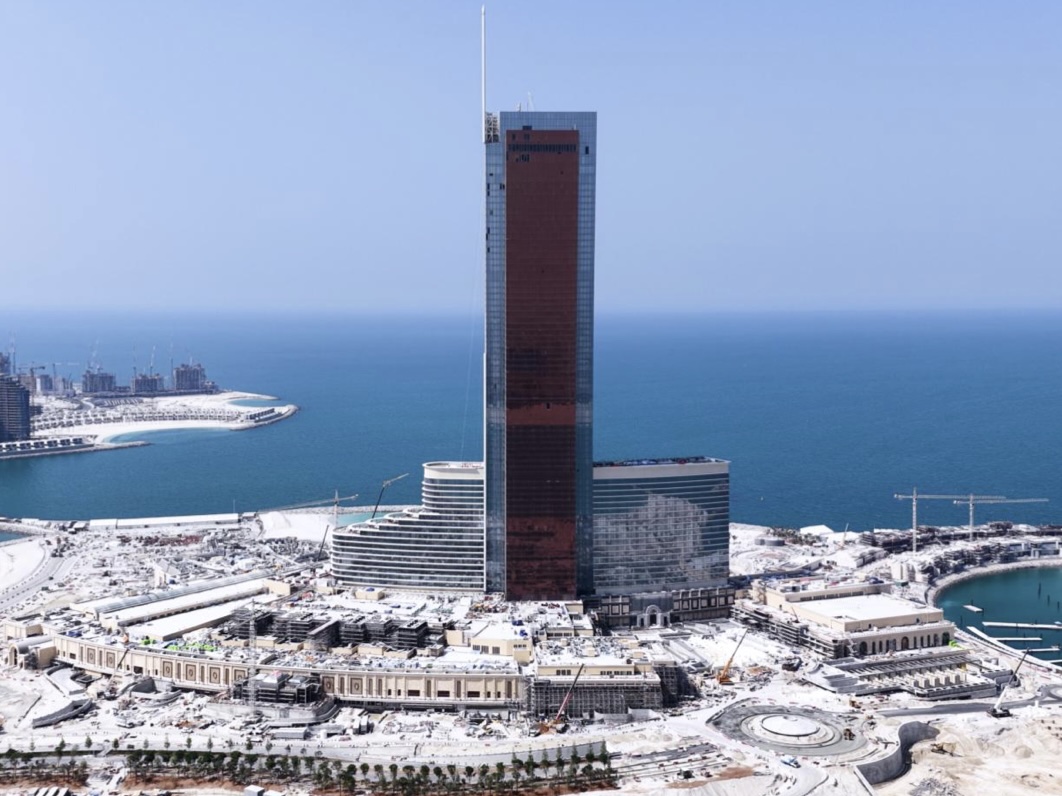

The scheduled opening of US$5.7 billion UAE integrated resort Wynn Al Marjan Island in September 2027 should significantly strengthen the financial position of Wynn Resorts, potentially opening the door for credit rating upgrades, according to CBRE Credit Research.
In a Monday note, CBRE analysts Colin Mansfield and Connor Parks said the Wynn Al Marjan Island project – of which Wynn holds a 40% equity interest – would have a “large de-leveraging effect” on the company’s financial metrics, with its lease-adjusted leverage expected to fall to around 5.0x in 2027 once the IR is operational and generating cash flow.
This, they observed, would represent an improvement of more than 1.0x compared with CBRE’s forecast for 2026, the final full year before Wynn Al Marjan Island is slated to open.
Notably, the analysts believe Wynn will deleverage no matter how Wynn Al Marjan Island’s debt is treated by the investment community.
Wynn Al Marjan Island is being financed separately through a project-level US$2.4 billion secured term loan facility, with the borrowing undertaken by a subsidiary of Island 3 AMI FZ-LLC – the joint venture between Wynn, Marjan and RAK Hospitality Holding LLC of which Wynn holds 40%. The project-level debt is also “non-recourse” to Wynn Resorts, meaning lenders’ claims are generally limited to the project and its associated assets rather than the wider Wynn group.
CBRE said it believes most investors will therefore incorporate Wynn’s share of the cash generated by Wynn Al Marjan Island into its earnings and cash flow metrics without adding any portion of the project’s debt to its consolidated leverage calculations.
“We believe most of the investment community will incorporate the reported cash inflows from Wynn Al Marjan Island into Wynn EBITDA, while not consolidating any portion of the project-level debt given it is non-recourse and the project is essentially majority owned by the government,” the analysts wrote.
CBRE said it saw merit in this approach given the sovereign-backed majority ownership structure, although the analysts acknowledged there was an argument for including at least some of Wynn Al Marjan Island’s debt in Wynn’s financial metrics. Nevertheless, even under a more conservative scenario in which Wynn’s proportional share of the debt and EBITDA were incorporated into its financial metrics, CBRE estimates the company would still achieve approximately 0.6x of deleveraging following the resort’s opening.
As such, they expect Wynn Al Marjan Island to materially improve Wynn’s credit profile regardless of how the project’s debt is treated.
With this in mind, the analysts have described Wynn as an “upgrade candidate” at Moody’s upon the opening of Wynn Al Marjan Island, with Moody’s having a 6.0x upgrade trigger pending strong positive free cash flow. They also noted that other ratings agencies S&P and Fitch both have 5.0x leverage upgrade triggers at the current “BB-” rating.
“After Wynn Al Marjan Island opens, Wynn should enter a prolonged period of lower leverage and robust free cash flow without any meaningful development capex on the horizon,” they said.
A higher credit rating could be significant for Wynn by improving its access to capital markets and allowing it to secure debt financing on more favorable terms.
In its earnings call last Friday (Asia time), Wynn management pointed to Texas and Georgia as attractive greenfield opportunities should political will turn positive for the land-based gaming sector while also revealing that thought had begun turning to how the company could potentially develop its excess Las Vegas Strip land.
RelatedPosts