


Macau’s Galaxy Entertainment group bucked the trend in the September 2026 quarter, reporting a 4% year-on-year and 7% quarter-on-quarter increase in group net revenue to HK$12.7 billion (US$1.62 billion) – including GGR of HK$12.9 billion (US$1.65 billion). The quarter was aided by a high VIP hold rate of 4.8%, with Adjusted EBITDA climbing 10% year-on-year and 9% quarter-on-quarter to HK$3.7 billion (US$472 million).
Despite this, the company showed resilience throughout the third quarter at a time when most Macau operators have faced significant headwinds that have cut into both revenues and profits.
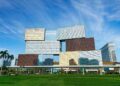
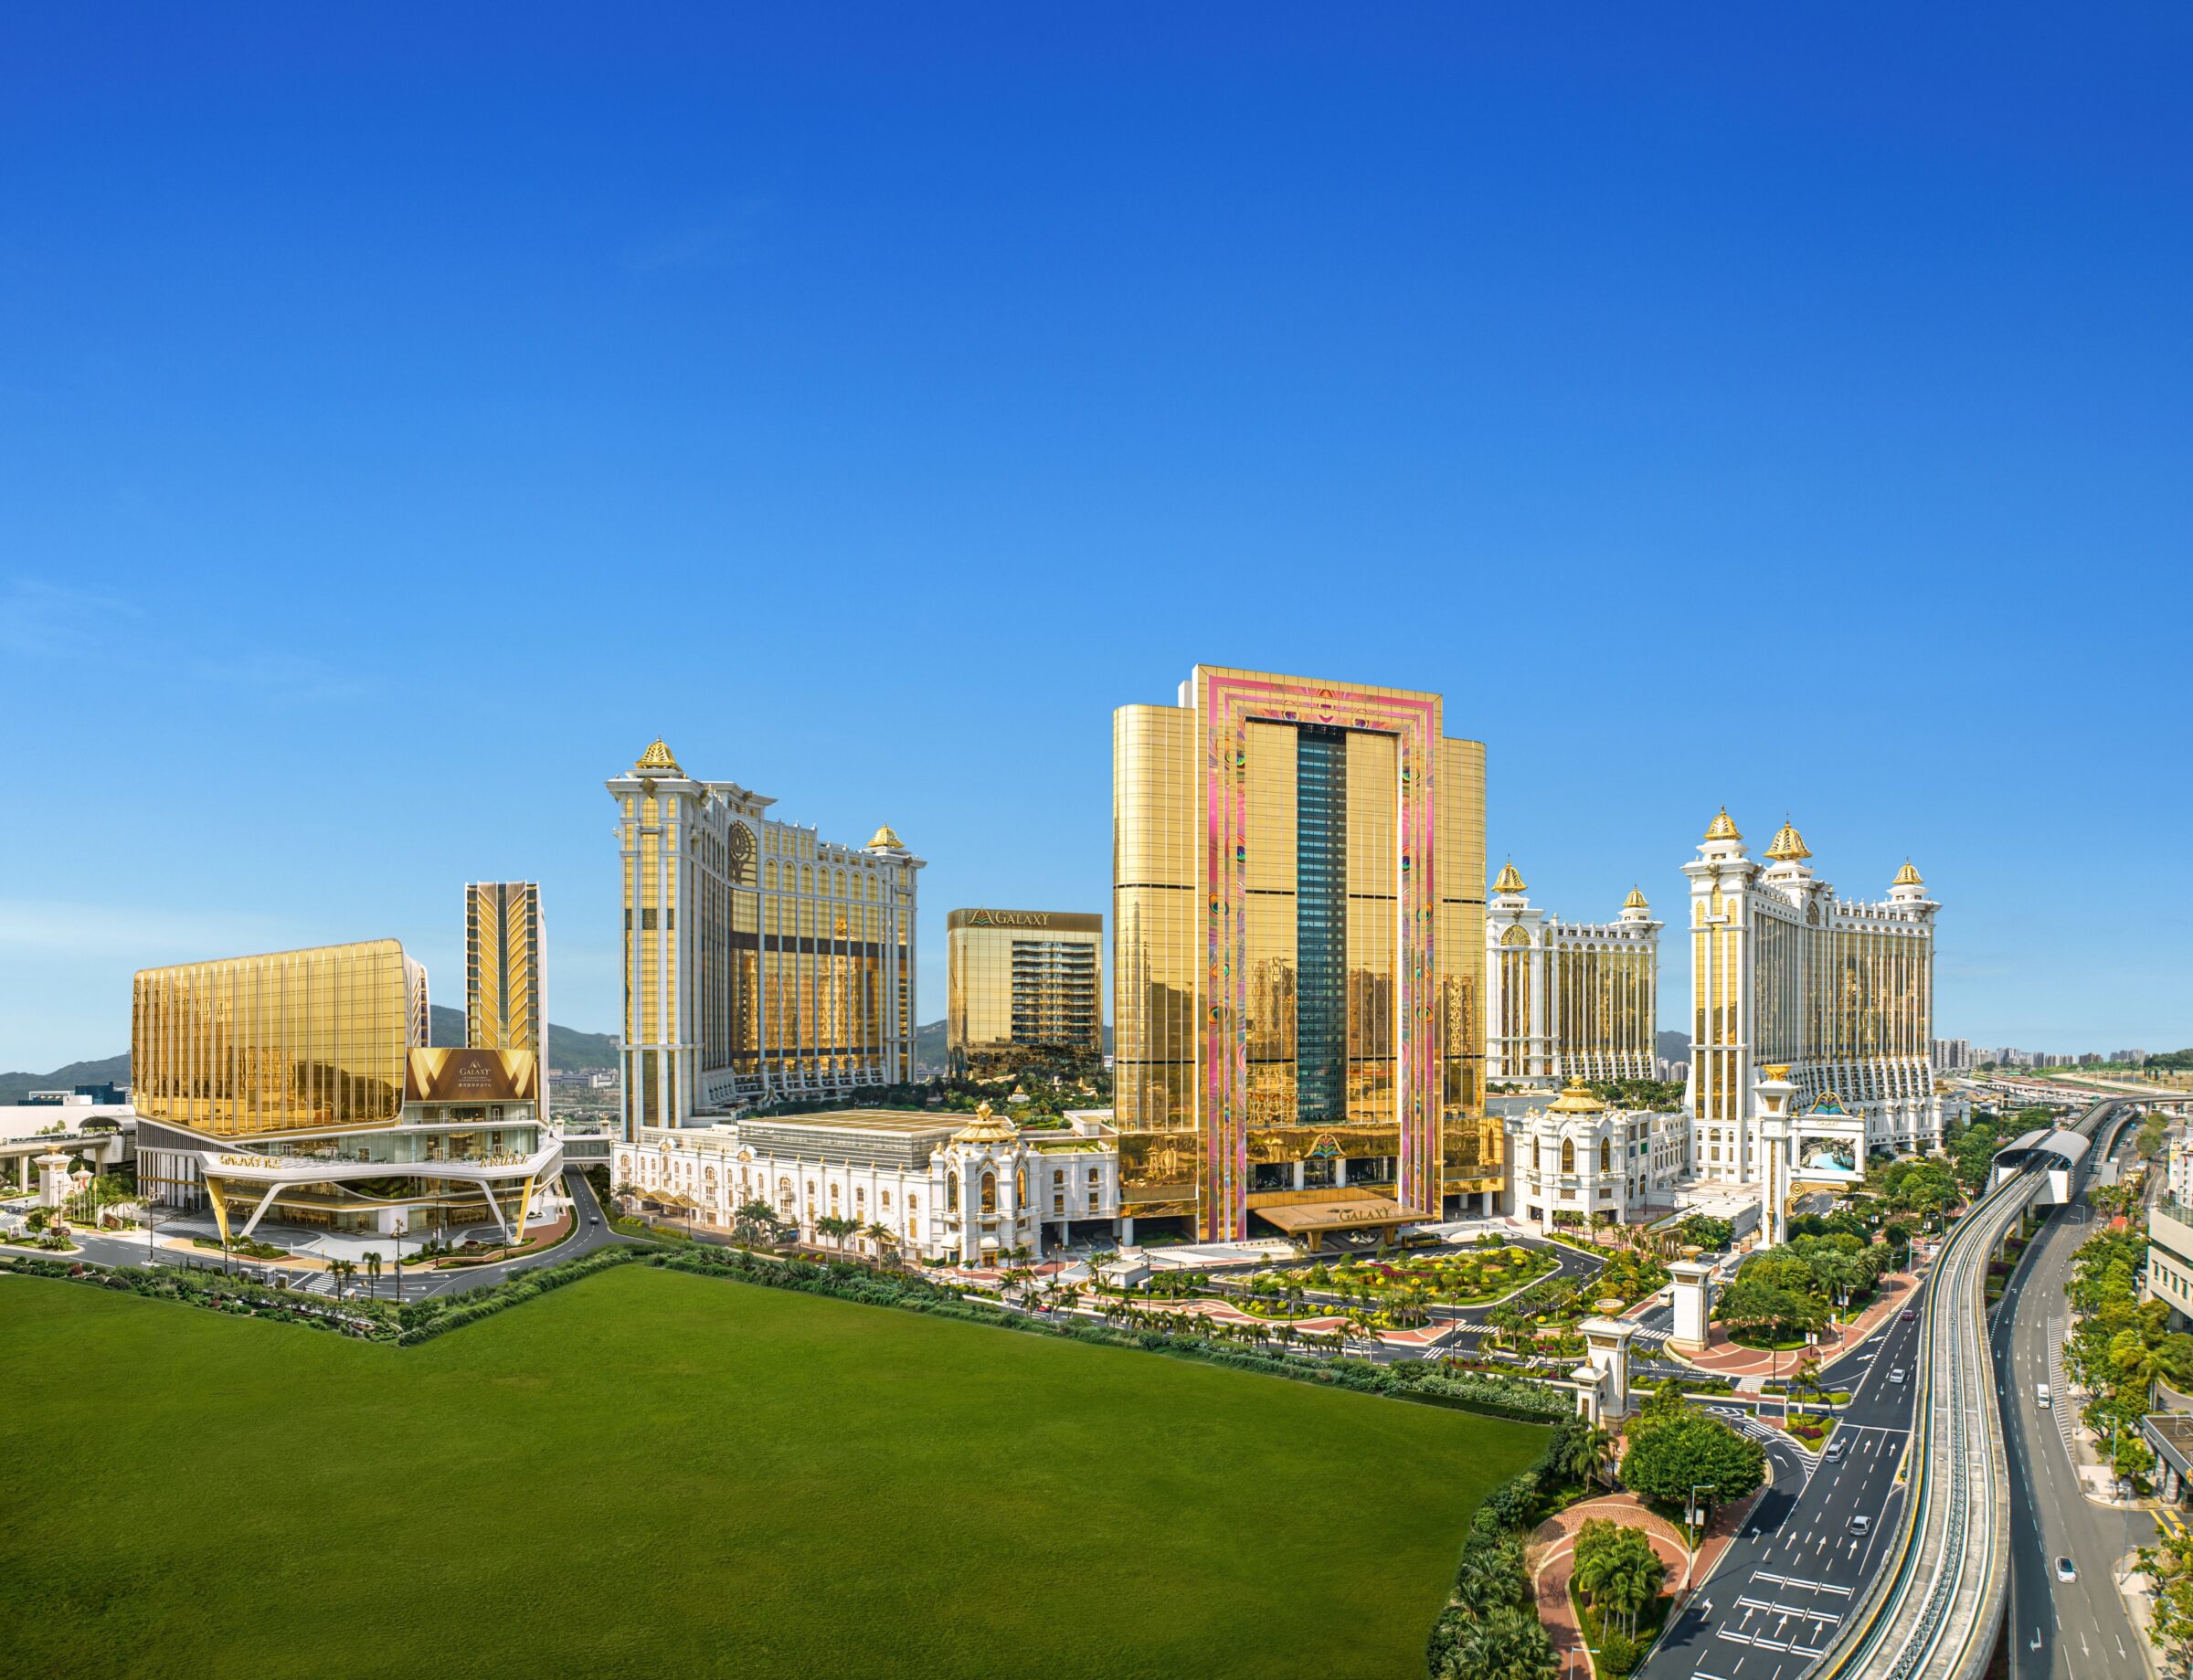
According to financial information published Friday, flagship property Galaxy Resort – until recently better known as Galaxy Macau – recorded a 7.4% year-on-year increase in total net revenue to HK$10.8 billion (US$1.38 billion) with Adjusted EBITDA up 15.3% to HK$3.54 billion (US$452 million) on a healthy 33% margin.
Rolling chip volume at the property was down 5.6% year-on-year but was 15.4% higher than the June quarter, while the 4.7% win rate saw rolling chip win soar both year-on-year and sequentially to HK$2.86 billion (US$365 million).
Mass table drop was slightly down, resulting in a 1.3% year-on-year fall in mass win at Galaxy Resort to HK$8.10 billion (US$1.03 billion). Slots win was up 16.7$ year-on-year but down 14.3% quarter-on-quarter to HK$677 million (US$86.4 million).
At StarWorld on the Macau peninsula, net revenue of HK$1.13 billion (US$144 million) was down 10.6% year-on-year and 7.6% quarter-on-quarter, with Adjusted EBITDA of HK$279 million (US$35.6 million).
The property also saw GGR decline by 12.8% compared with 3Q25 and by 11.3% compared with the June 2026 quarter to HK$1.24 billion (US$158 million). Notably, with hotel renovation works ongoing at StarWorld, rolling chip volume plummeted from HK$971 million (US$124 million) a year earlier to just HK$200 million (US$25.5 million), but an exceedingly high win rate of 10.2% on that lower volume saw rolling chip win reach HK$21 million (US$2.7 million) – just below the HK$24 million (US$3.1 million) in 3Q25. Mass table win of HK$1.10 billion (US$140 million) was down 11.8% year on-year and slots win of HK$121 million (US$15.4 million) down 20.9%.
GEG Chairman Francis Lui said in prepared remarks that the FIFA World Cup temporarily affected customer traffic and gaming activity during the early part of the quarter although the impact was short-lived.
“Business recovered quickly following the tournament, supported by strong summer visitation and healthy activity across both gaming and non-gaming offerings,” he said, pointing to recent additions to the portfolio at Galaxy Resort for maintaining visitation.
“Our premium offering continued to make good progress during the quarter. Capella at Galaxy Macau ramped up well and the expansion of Horizon Plus from six to 10 private salons provided additional capacity to meet the demand from high-value customers and strengthened our position in the premium market. Together with Raffles at Galaxy Macau and Horizon Club, these products give us a strong and differentiated premium portfolio.”
On StarWorld, Lui added, “The hotel renovation program continued during Q3. While the temporary reduction in available room inventory affected the property’s EBITDA by approximately HK$20 million during the quarter, we carefully managed the works to minimize disruption and maintain service standards. The upgraded rooms and suites will enhance the property’s appeal to premium customers, with completion targeted for the first quarter of 2027.”
The GEG Chairman also reiterated his confidence in Macau’s long-term advantages, even while short-term headwinds continue to disrupt the market.
“We acknowledge that GGR growth has moderated in the near term, reflecting a combination of short-term factors, including possibly taxation policy changes, slower global economic growth and ongoing geopolitical uncertainty,” he observed.
“Despite these near-term factors, we remain confident in the medium- to longer-term outlook for Macau. This view is underpinned by the continued growth in China’s economy and household wealth, which should support sustained demand for leisure, tourism and travel. GEG is well positioned to capture these longer-term opportunities through our world-class integrated resorts and the largest development landbank in Macau.”
RelatedPosts