

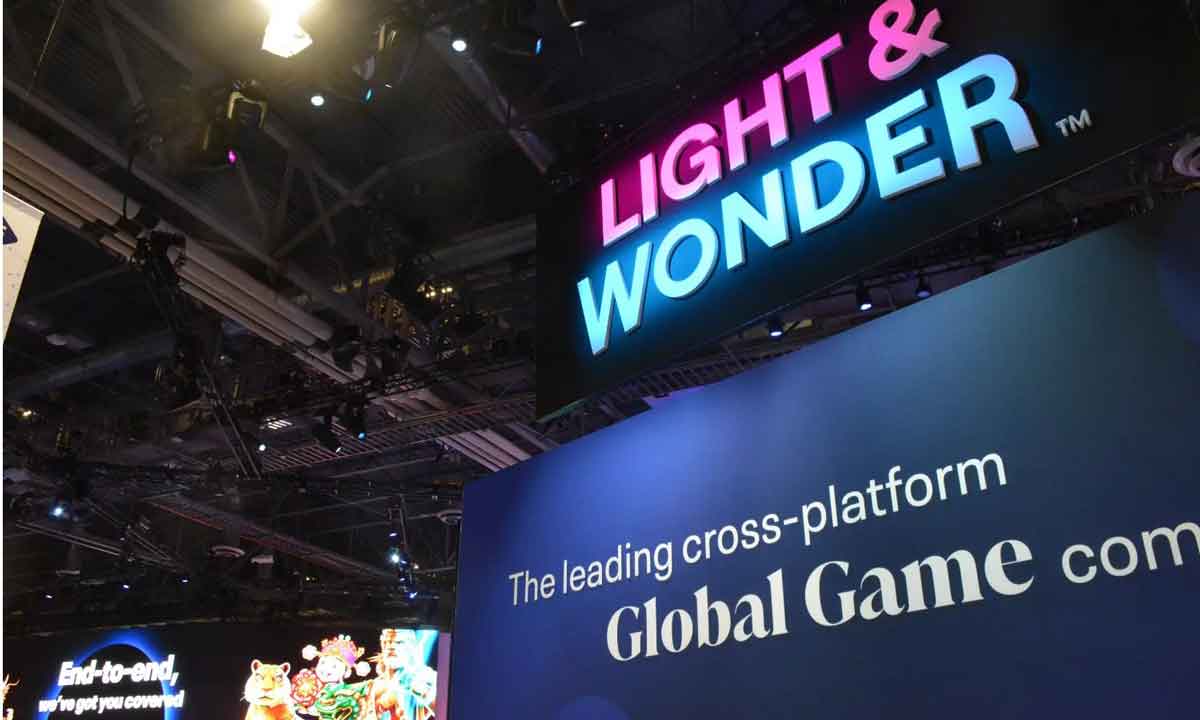

Global gaming supplier Light & Wonder reported a 7% year-on-year increase in adjusted net profit after tax to US$163 million in the three months to 30 September 2026, citing EBITDA growth and improved margins alongside the strong performance of its Gaming and iGaming segments.
While group-wide revenue fell 2% year-on-year to US$824 million on softness in systems and social gaming arm SciPlay, Gaming revenue increased 3% year-on-year to US$248 million, which the company said reflected underlying growth in its North American installed base and average daily revenue per unit.
Gaming machine sales increased 5% to US$199 million, although gaming systems revenue declined 24% to US$55 million and table products revenue fell 7% to US$52 million, driven by the timing of utility sales.
iGaming delivered 13% revenue growth to US$97 million, while SciPlay revenue decreased 12% to US$173 million, continuing to reflect ongoing softness in the broader social casino free-to-play market.
Net income rose 17% year-on-year to US$133 million, compared with US$114 million a year earlier, while consolidated Adjusted EBITDA increased slightly to US$383 million, driven by “favorable revenue mix shifts and ongoing operational efficiencies” that led to continued margin strength.
“Our content-centric operating model is enhancing our recurring revenue business, as evidenced in the results,” said Light & Wonder President and CEO Matt Wilson.
“Sustained investment in studios and content is driving strong franchise performance across the portfolio, and our roadmap was well received at both AGE and G2E, which builds our confidence heading into the fourth quarter and 2027. Gaming momentum continues, evidenced by our North American premium installed base growing for the 25th consecutive quarter. Further, Grover continues to scale across both existing and new markets.
“We’re encouraged by the momentum heading into the fourth quarter, with positive feedback from customers following the trade shows, customer purchase intentions and recent industry data. To maximise both customer and shareholder value, we expect to leverage this momentum while staying focused on disciplined execution that drives strong cash flows and allows us to reinvest in product innovation and talent while further reducing leverage to deliver on our commitment.”
Light & Wonder said it reduced outstanding debt by US$153 million during the third quarter to around US$5 billion, with its net debt leverage ratio narrowing slightly to 3.3x.
“Importantly,” said CFO Oliver Chow, “we’re also investing deliberately across R&D and Gaming operations capital expenditure, as well as in AI and infrastructure to support both growth and efficiency across the business over time.
“We remain committed to prioritising this deleveraging path in the fourth quarter and beyond, as we continue progressing toward our long-term financial targets.”
Light & Wonder recently set a target of US$2 billion in Adjusted EBITDA by 2028, having already achieved its previous goal of US$1.4 billion by 2025.
RelatedPosts