
Financial research firm CreditSights says it views Genting Bhd’s newly announced rights issue positively from a credit standpoint but noted the improvement to credit metrics is modest.
In a Tuesday note, CreditSights observed that the right issue, which aims to raise MYR1.25 billion (US$306 million), marks a “welcome shift away” from the group’s traditional reliance on debt funding and “signals shareholders’ willingness to share the deleveraging burden.”
This comes with the group holding MYR26.1 billion (US$6.4 billion) in net borrowings as of 31 March 2026 and major capex commitments that include its US$5.5 billion expansion of Resorts World New York City via Genting Malaysia and US$5 billion reimagining of Resorts World Sentosa via Genting Singapore.
The rights issue could, the research firm explain, reduce leverage by between 0.2x and 0.3x to around 4.3x.
While shares in Genting Bhd fell by around 20% following the rights announcement, CreditSights said it does not expect any shareholder resistance given it only requires an ordinary resolution and has strong backing by the Lim family, whose 45.1% stake provides a substantial voting bloc in favor of the rights issue. The Lim family has also committed to subscribe for MYR564 billion (US$138 million), representing their full stake, with likely to be used to address upcoming bond maturities.
CreditSights pointed out that the Lim family’s subscription ensures the public float remains above 25% and that a mandatory takeover offer of Genting Bhd will not be pursued, with a mandatory offer triggered if the Lim family acquires over 2% of additional voting stake within any rolling 6-month period.
It also believes the group’s current debt situation will prevent any further moves by Genting Bhd to pursue any debt-funded takeover attempts of Genting Malaysia in the next 12 to 18 months in order to preserve balance sheet strength and avoid further leverage and rating downgrade risks.
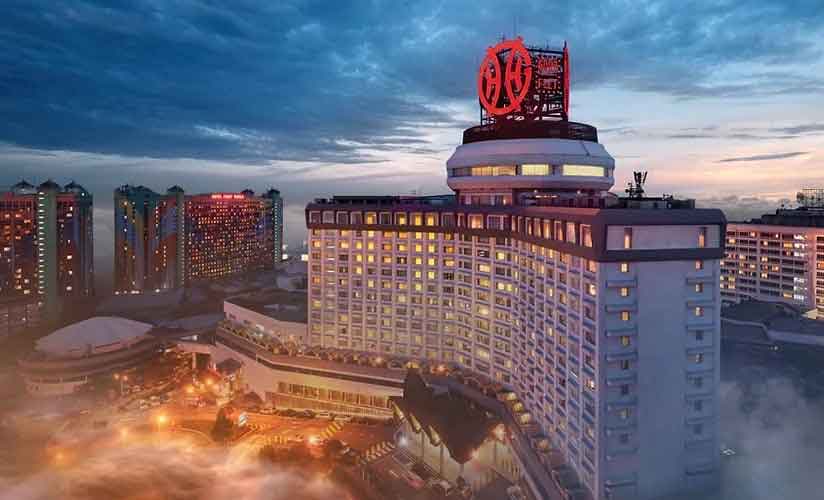
Genting Bhd last year lifted its stake in the Malaysian subsidiary – which counts the New York assets as well as Malaysia’s Resorts World Genting among its core assets – from 49.36% to 73.13% via a voluntary takeover offer. This fell short of the 75% required to take Genting Malaysia private, although the parent has since lifted its stake to 73.8% via on-market purchases.
Instead, CreditSights expects the group to focus further on deleveraging opportunities, among them non-core asset sales such as its unused Miami land parcels.
While dividend curtailments, perpetual security issuances and earnings improvements are viewed as insufficient to turn the tide amid the very heavy capex pipeline, CreditSights remains positive on the long-term outlook – despite S&P Global Ratings recently warning that Genting Bhd is at risk of becoming a “fallen angel.”
Mitigants to this include positive earnings takeaways such as robust ramp in New York and improvement in Las Vegas and Singapore, dividend prudence, robust liquidity and the possible Miami land sale.
RelatedPosts