
Macau concessionaire SJM Resorts, S.A. has reduced its staff count by 5% since the start of the year and is rolling out several more initiatives to reduce operating expenses and improve leverage, according to information from CBRE Equity Research.
In a note following SJM’s 2Q26 earnings call earlier this week, which was not open to media, CBRE explained that SJM management remains focused on improving operating expense efficiencies because elevated labor costs following the closure of all satellite casinos last year continue to impact margins.
Under Macau law, concessionaires were required to absorb all satellite employees even while scaling down operations. SJM was by far the most heavily impacted, having controlled nine of Macau’s 11 satellite casinos heading into their final year of operation in 2025.
According to CBRE, SJM revealed during its earnings call that its staff count had since fallen by 5% over the past seven months and that it has rolled out “several other initiatives” to further improve margins by yearend.
“As the company’s opex efficiencies and controlled reinvestment strategy begin to drive cash flow generation, management plans to direct its proceeds to reducing leverage,” wrote CBRE’s John DeCree and Max Marsh.
SJM reported this week a widened loss of HK$295 million (US$37.6 million) in the six months to 30 June 2026 due to elevated costs related to its satellite closures, which also resulted in group-wide GGR falling 18.5% year-on-year to HK$12.1 billion (US$1.54 billion) – despite all properties recording year-on-year improvement.
However, CBRE pointed out that SJM gained 40 bps of GGR share on a sequential basis in Q2 with management citing some success with targeted customer-experience and product enhancements. The company also revealed that GGR market share improved each month throughout the quarter, reaching 10.8% in June – SJM’s highest monthly total since closing its satellite casino operations in October 2025.
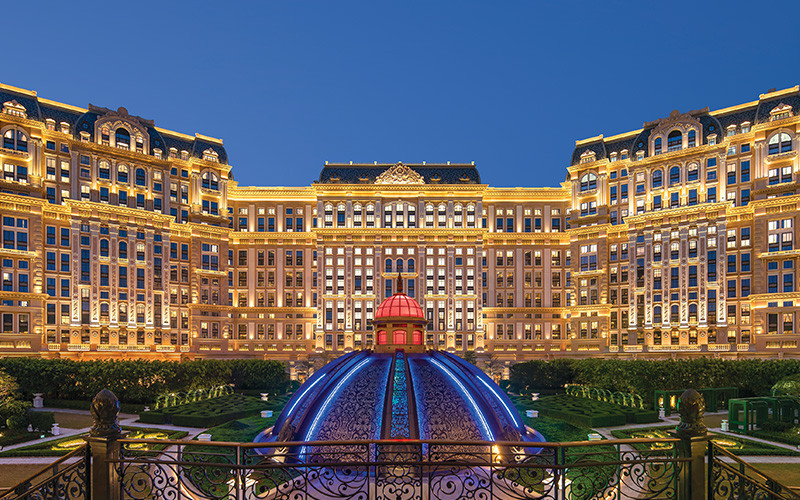
These gains were in part driven by rising VIP volume and hold rate at Grand Lisboa Palace in Cotai, although mass market operations at the integrated resort remain subdued while the company undertakes a substantial renovation of the mass gaming floor. The renovation will be completed in stages according to SJM management with a view to minimize disruption but CBRE stated that some impact is inevitable until the works are complete in 1H27.
The analysts added, “While progress in VIP is encouraging, this business is inherently volatile and highly competitive. GLP still needs to find more share of the mass market segment to drive higher margins and cash flow.”
CBRE is maintaining a “HOLD” rating on SJM shares but has lowered its price target from HK$2.50 to HK$1.50.
“Macau remains highly competitive and the revenue loss (and opex burden) from the closure of SJM’s satellite casino business has been difficult to overcome,” said DeCree and Marsh.
“SJM is making some progress on both opex and market share, however, we still see an arduous path to deleveraging.”