

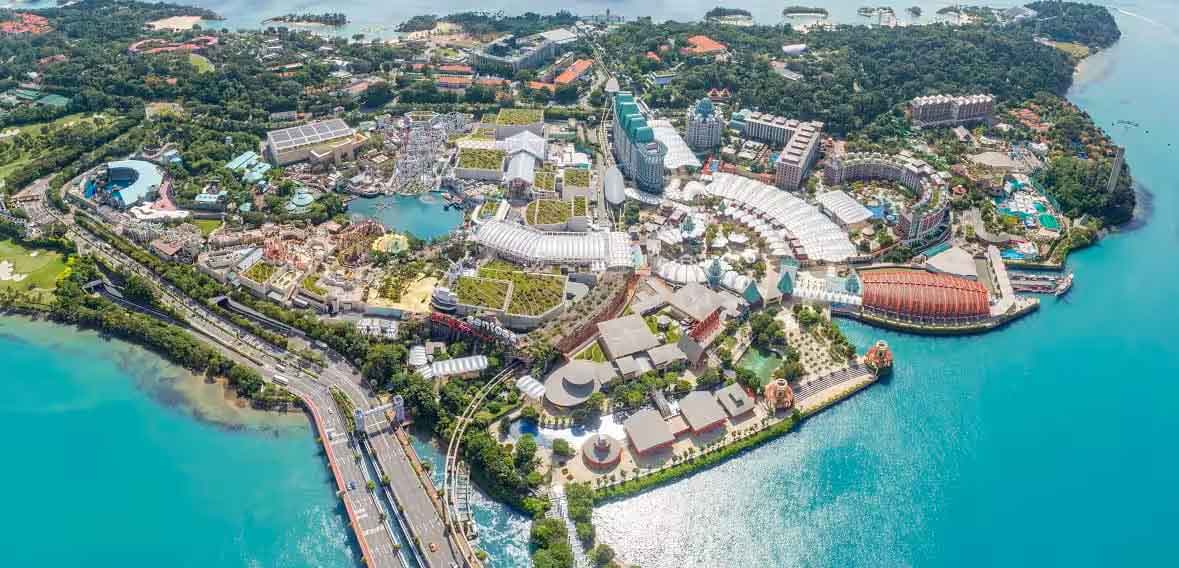

Genting Singapore’s Resorts World Sentosa (RWS) drove significant improvement in its Singapore market share in the June 2026 quarter following a disastrous Q1, however real recovery will depend on the performance of its RWS 2.0 transformation project, according to Maybank.
After RWS managed to keep its gaming revenue largely flat in 2Q26 at SG$401 million despite the global headwinds that have negatively impacted many regional operators, Maybank analyst Samuel Yin Shao Yang said in a note that a 21% quarter-on-quarter uptick in VIP volume had seen the property’s VIP volume share recover to 36% from just 19% in the March quarter.
This comes after duopoly rival Marina Bay Sands recently reported a 7.4% quarter-on-quarter decline in net revenues and a 7% decline in rolling win in Q2, pointing to a clear impact from the World Cup on its premium player volumes in June.
According to Yin, RWS also saw its mass market GGR share rise slightly from 26% to 27% on a 2% improvement in mass revenues.
However, he added that RWS itself considered this a quarter of normalization after “poorly executed ‘self-inflicted’ 1Q26.”
As such, “The real earnings re-rating catalyst still depends on RWS 2.0, with SG$1.8 billion invested to date, delivering stronger visitation and gaming revenue from FY27 onward.”
Maybank has further cut its earnings estimates by 17% for 2026, by 15% for 2027 and by 14% for 2028.
RelatedPosts