
Deleveraging no longer appears to be a primary focus for Wynn Macau Ltd, with the company instead looking to drive incremental EBITDA to support margin growth, according to financial research firm CreditSights.
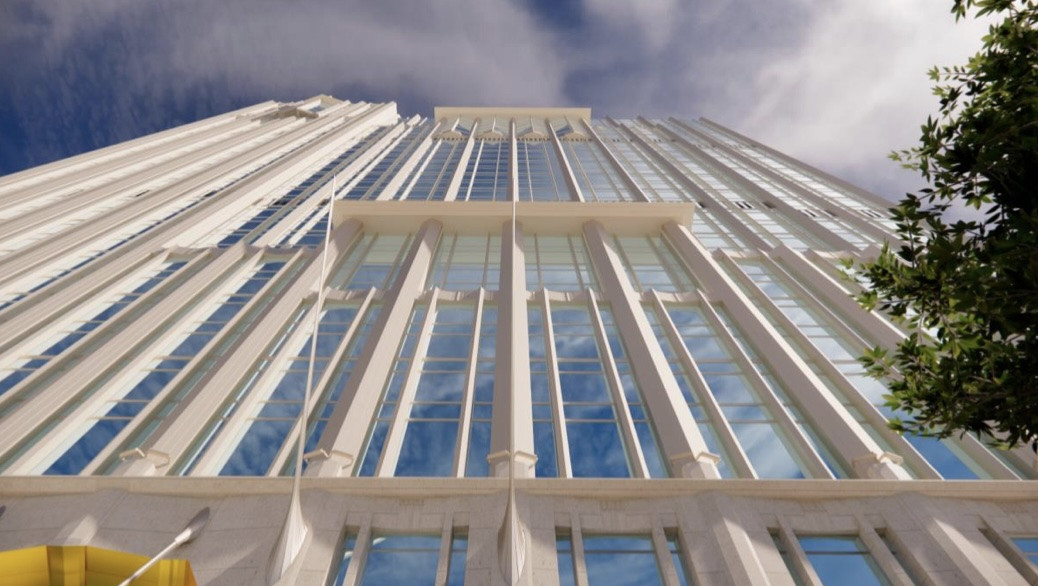
The analysis followed confirmation late last week that Wynn has been granted permission by the Macao SAR Government to proceed with development of a new 432-room, all-suite hotel, theater and event center, The Enclave, at Wynn Palace. The project is forecast to cost up to US$950 million.
 In a Friday note, CreditSights said financing for The Enclave could come from available cash or, if that fell short, by drawing down on an undrawn US$1.35 billion revolver.
“While this would likely put a strain on Wynn Macau’s leverage metrics, which still remain above pre-pandemic levels), we opine that deleveraging has become a lower priority for the company, as evidenced by its stagnant leverage levels over the past several quarters,” said CreditSights analysts Nicholas Chen and David Bussey.
“Management appears more focused on driving incremental EBITDA to support margin preservation/growth.”
CreditSights stated that it expects to construction of The Enclave to commence this year with capex limited to piling and early development works before, however spend will increase substantially post-2026. It also pointed to previous guidance provided by Wynn Macau management which put FY26 capex at US$400 million to US$450 million and FY27 capex at between US$700 million to US$750 million.
The financial research firm added that it calculates Wynn Macau to have generated around US$91 million of free cash flow in the first three months of 2026.
“For FY26, we project free cash flow to remain positive, albeit smaller year-on-year due to the higher expected capex outlay,” the analysts said.