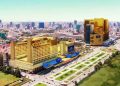
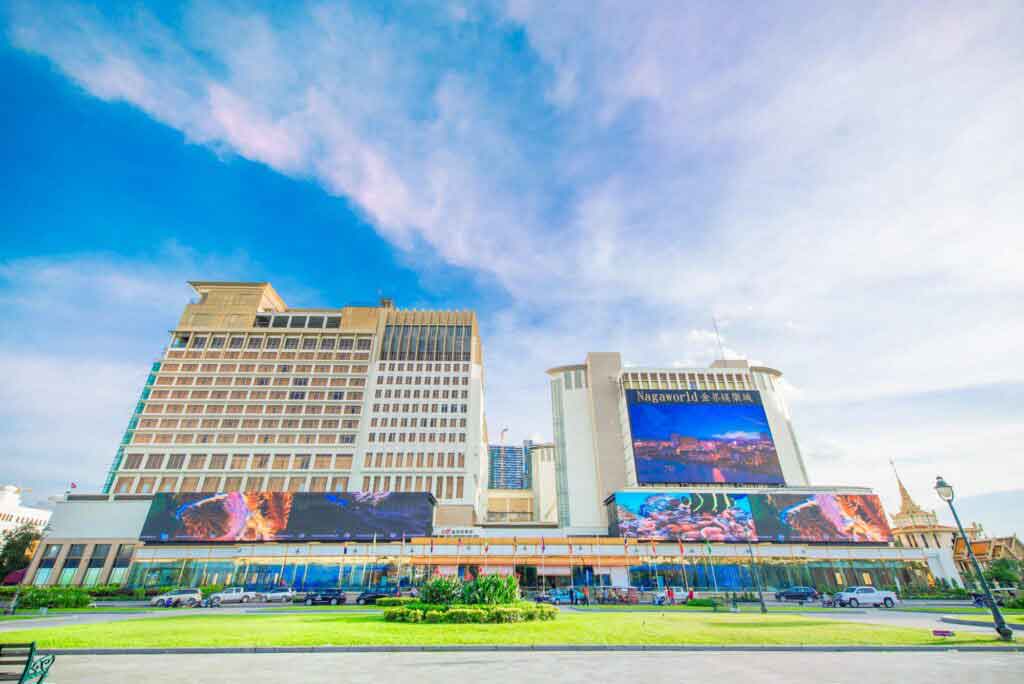

S&P Global Ratings has upgraded NagaCorp, operator of monopoly integrated resort NagaWorld in the Cambodian capital of Phnom Penh, from “B” to “B+” – citing a healthy balance sheet anchored by low leverage and a sizable cash balance.
However, it has warned that earnings are unlikely to return to pre-pandemic levels anytime soon due to the company’s former reliance on junket VIP, which could create challenges in the coming years should NagaCorp increase dividend payments and start development of its planned Naga3 expansion.
The ratio of debt to EBITDA, estimated at 0.3x across 2026 and 2027, would under S&P’s stressed scenario near 3x in 2029 when dividend payouts reach 60% and US$650 million is spent on capex annually.
The ratings agency noted that although NagaCorp enjoyed an earnings recovery in 2025, with revenue growing to US$713 million and EBITDA to US$404 million, this remains well below pre-pandemic levels. In 2019, reported revenue and EBITDA at NagaWorld were US$1.8 billion and US$667 million respectively supported by the referral VIP segment – primarily junkets – which contributed around 70% of gross gaming revenue.
“This segment is unlikely to return and will weigh on the company’s business strength,” S&P said. “We expect Naga’s earnings to grow modestly over the next two years, at 5% to 6% annually across 2026 and 2027. A return to the level of earnings in 2019 is unlikely for the time being.”
S&P added that future shareholder returns and Naga3 capital spending will remain key watchpoints for NagaCorp’s new rating, with 2026 capex estimated at around US$170 million in 2026 before an increase to about US$380 million in 2027 for Naga3 and annual shareholder returns at US$100 million to US$120 million.
RelatedPosts