S&P Global Ratings has downgraded the secured debt of New York’s Empire Resorts from “B+” to “B” with a negative outlook amid concerns over its ability to refinance a looming US$300 million bond maturity due in November.
The “B” rating indicates that Empire’s debt profile is speculative or highly vulnerable to adverse conditions, albeit with the capacity to meet current commitments.
In a note, S&P hinted that Empire’s capacity may revolve around the appetite of its parent, Genting Malaysia, to come to the rescue should the US-based entity fail to obtain a successful refinancing.
Observing that Empire’s refinancing risk has significantly increased given that the company has yet to make any material progress regarding its bond maturing in November 2026, the ratings agency pointed out that any successful refinancing now depends on elements beyond Empire’s control, including the market environment, investors’ risk appetite and yield conditions.
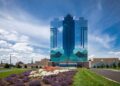
The Genting Group had planned to avoid any refinancing need by selling of a raft non-gaming assets associated with Empire’s New York state IR, Resorts World Catskills (RWC), and lease them back.
However, that deal was ultimately put on hold, creating an unexpected delay to refinancing.
According to S&P, Empire’s unrestricted cash balance and operating cash flow will be less than US$20 million for the 12 months ending 31 December 2026 – significantly short of the US$300 million bond and with other capital costs expected to accrue. It also noted that, while the company’s EBITDA has turned positive since 2021, operating conditions remain challenging with negative free operating cash flow forecast over 2026 to 2028.
That makes Genting’s financial strength crucial, with the Malaysian gaming giant having already tipped into US$740 million since 2018.
“Our rating on Empire reflects our view that Genting group will continue to provide support,” S&P said.
“We believe Empire’s status as a going concern is important for the preservation of Genting’s reputation, as well as the group’s relationship with the New York state gaming regulators. Empire holds two of the group’s four gaming licenses in the state of New York.
“We believe the group is involved with Empire’s refinancing, and could provide support should other refinancing options fail.”
Aside from RWC, Empire’s assets include Resorts World Hudson Valley and mobile sports wagering operator Resorts World Bet.
RelatedPosts