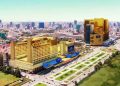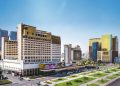


NagaCorp, operator of Cambodia’s only integrated casino resort NagaWorld in Phnom Penh, will likely cut by half the US$3.5 billion it originally planned to spend on its upcoming Naga 3 expansion, according to investment group CLSA.
Initiating coverage with an “Outperform rating” – indicating an expectation that the stock will exceed market benchmarks – CLSA analyst Jeffrey Kiang said the collapse of key junket operators in the years since Naga 3 was first envisioned has altered the playing field for NagaCorp. As such, the company is expected to reduce spending on the expansion project to around US$1.75 billion.
While NagaCorp has not stated as such, it did in December cancel a US$1.75 billion share subscription agreement with its controlling shareholder. This follows the company previously postponing the development by four years due to economic challenges posed by the COVID-19 pandemic.
“So we assume,” Kiang wrote, that “Naga 3’s total capex will be lowered by roughly half to US$1.75bn, as NagaCorp’s referral VIP business has been structurally diminished by shutdowns of certain junkets in Macau in 2021 to 2022.”
CLSA added that they expect the payback period for Naga 3 to be four to five years, aided by strong profit growth, although dividend payouts are unlikely to exceed 30% given that construction of Naga 3 with internal funding “should be a key priority for the company, given its high cost of capital relative to its asset profile.”
The investment group said NagaCorp should benefit from increasing foreign direct investment and a weaker US dollar in the coming years, forecasting net profit to increase at a 12% CAGR from 2025 to US$376m in 2027.
“While the aforesaid tailwinds should support NagaCorp’s revenue, improved operating efficiency and lower interest on liabilities ahead should reduce the cost burden,” CLSA stated.
RelatedPosts