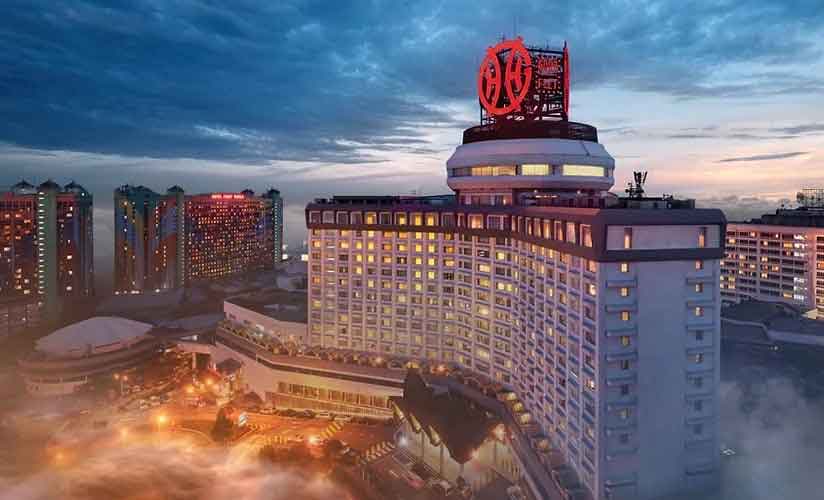

Malaysia’s Genting Group is facing looming debt maturities totaling almost US$3.5 billion, but financial research firm CreditSights believes the refinancing risk is manageable given the group’s wide range of funding options.
The sizeable debt parcels due to mature in 2026 and 2027 include a US$1.5 billion bond held by group holding company Genting Overseas Holdings Limited (GOHL), a US$300 million Empire Resorts bond, US$665 million in term loans at Resorts World Las Vegas and MYR3.8 billion (US$968 million) of assorted Malaysia retail bonds.
In a lengthy research note, CreditSights analysts Jonathan Tan Jun Jie and R Lakshmanan said Genting’s most likely strategy in addressing the debt – particularly the cornerstone maturity that is the GOHL bond – will be a mix of internal cash, dividends and partial market refinancing rather than reliance on operating subsidiaries directly.
They suggested that dividends from Resorts World Sentosa operator Genting Singapore, in which Genting holds a majority 52.8% stake, loom as a key source, with the subsidiary potentially paying an unusually large or special dividend if needed due to its strong cash position.
“A bold 100% to 150% payout ratio assumption could generate net annual dividend income of US$175 million to US$290 million for GOHL,” CreditSights wrote. “We believe Genting Singapore has the financial strength to make such a large dividend payout even amid its ambitious US$5 billion RWS 2.0 expansion through 2030, though this will result in cash leakage to the 47% minority shareholders of Genting Singapore.”
The analysts added that additional dividend and brand-fee income from Genting Malaysia and other subsidiaries can also be up-streamed to support refinancing, while Genting itself typically holds US$200 million to US$330 million of standalone cash which can be applied to the bond.
Genting also boasts good access to capital markets and could issue new US-dollar bonds, likely in the range of US$500 million to US$800 million, or issue Malaysian-ringgit retail bonds where it is a frequent and successful issuer, the analysts explained.
According to CreditSights, the US$300 million Empire bond is expected to be repaid from asset sales with remaining loans and retail bonds expected to be rolled over through established refinancing channels.
“We believe Genting has multiple refinancing options available,” the analysts continued. “Our base case scenario assumes the GOHL bond will be partly refinanced with standalone cash at Genting and new Malaysian retail bonds issued at GENT, and the rest repaid with dividend income up-streamed from Genting Singapore.”
RelatedPosts