

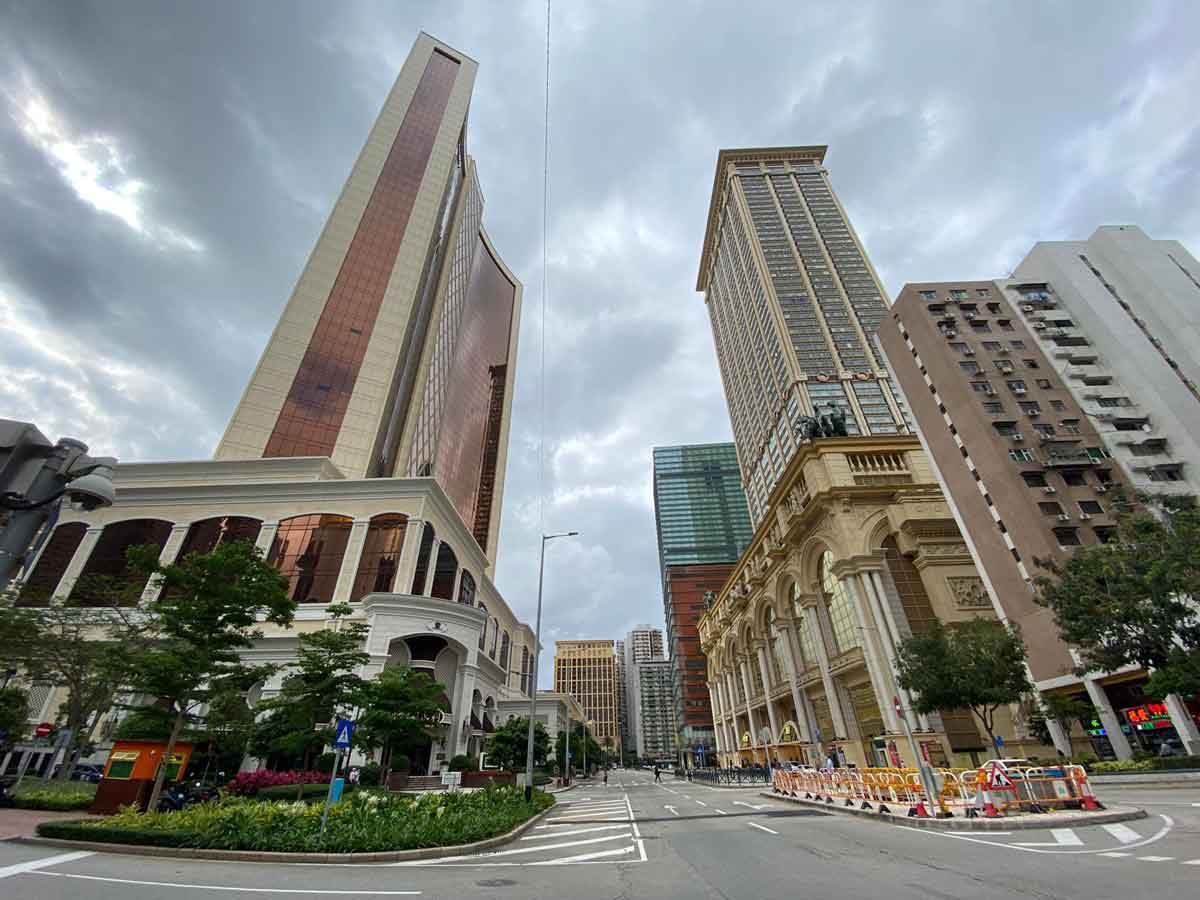

Moody’s Ratings says it expects SJM Holdings – the Hong Kong-listed parent company of Macau concessionaire SJM Resorts S.A. – to reduce its financial leverage substantially in 2026 on higher EBITDA and modest debt reduction.
It also expects SJM’s liquidity to be good, aided by the proposed issue of new senior unsecured notes, growth in gaming revenues and normalization of win rates at its Macau resorts.
Having this week assigned a B1 rating to SJM’s proposed notes, which remain unpriced at time of writing, and maintained its Ba3 negative rating on SJM. Holdings, Moody’s said it estimates the company’s Adjusted debt/EBITDA leverage rose from 7.4x at 30 June 2025 to between 8.3x and 8.7x at the end of the year, impacted by its weak 3Q25 earnings and the debt-funded acquisition of former satellite casino L’Arc Macau.
“Subsequently, we expect the financial leverage ratio will improve visibly to about 6.0x in 2026, driven by higher EBITDA and a modest debt reduction,” Moody’s stated.
“Higher earnings will be mainly supported by the reallocation of satellite casino tables to SJM’s self-owned properties and the newly acquired L’Arc Hotel. Other contributing factors include continued growth in gaming revenue, further ramp-up of Grand Lisboa Palace (GLP) and normalization of win rates.”
Moody’s has, however, issued a negative outlook for SJM on uncertainty around its organic earnings performance, customer retention and the extent of earnings generation from the satellite table reallocation.
Despite this, the ratings agency added, “We expect SJM’s liquidity to be good. Liquid sources from the proposed senior unsecured USD bond proceeds, in addition to cash holdings (excluding restricted cash) of HK$2.1 billion (US$270 million) as of end-June 2025 and its available revolving credit facility will be more than sufficient to cover its cash needs and maturing debt over the next 12 to 18 months.”