


MGM Resorts International’s integrated resort development in Osaka, Japan represents a significant credit risk for the US-based casino operator, although this is largely balanced by the group’s solid liquidity position, according to Moody’s Ratings.
That liquidity includes approximately US$2.4 billion in combined cash and more than US$4.9 billion in available revolving credit facilities held by MGM Resorts and its 56%-owned subsidiary, MGM China Holdings.
The assessment formed part of a credit update issued by the ratings agency this week, which affirmed MGM Resorts’ B1 Corporate Family Rating (CFR), B1-PD Probability of Default Rating and B1 rating on its senior unsecured notes, as well as MGM China’s senior unsecured notes rating at B1.
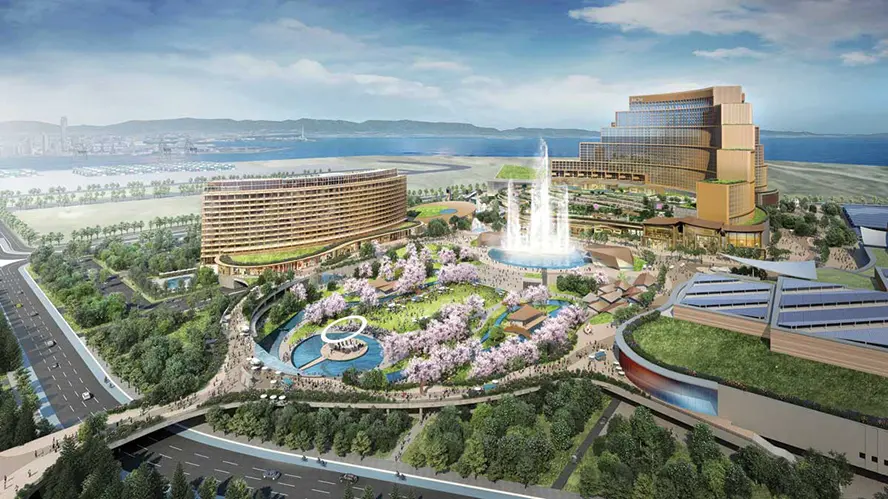
MGM Resorts holds a 56% stake in MGM China and a 40% interest in the US$10 billion MGM Osaka project, scheduled to open in 2030. The company recently revealed it would increase its annual deployment of capital into development of MGM Osaka to around US$1 billion a year in each of 2027 and 2028.
Nevertheless, Moody’s said its ratings affirmation reflects MGM’s relatively stable operating performance, with debt/EBITDA of 6.8x for the 12 months ended 30 September 2026.
The agency added, “We expect leverage to decline modestly, supported by growth in the online and digital business and lower lease obligations as MGM sells select regional operations.
“The ratings also incorporate MGM’s sizable development commitments, particularly MGM Osaka. These credit risks are balanced by its good liquidity.”
Moody’s said MGM’s B1 Corporate Family Rating also reflects its large scale, strong presence on the Las Vegas Strip and solid position across several regional US markets, with its presence in Macau through MGM China providing further support given the market’s favorable long-term prospects.
The agency noted that, as of 30 September 2026, MGM Resorts, excluding MGM China, held approximately US$1.8 billion in cash and cash equivalents, alongside an undrawn US$2.3 billion revolving credit facility expiring in February 2029. MGM China separately held approximately US$600 million in cash and had around US$2.7 billion in available capacity under its US$3 billion revolving credit facilities.
Moody’s said upcoming debt maturities, including US$750 million in MGM China notes due in February 2027 and US$675 million in MGM Resorts notes due in April 2027, were manageable given the group’s substantial cash reserves and available credit facilities. It added that the stable outlooks for both companies reflect expectations of relatively stable operating performance and good liquidity, with MGM expected to manage its debt maturities and development commitments while maintaining leverage broadly in line with current levels and achieving modest improvement over time.
RelatedPosts