
Regional expertise, worldwide
  • Subscribe
  • Magazines
  • About
  • Contact
  • Advertise
Thursday 29 October 2026
  • zh-hant 中文
  • ja 日本語
  • en English
IAG
Advertisement
  • Newsfeed
  • Mag Articles
  • Video
  • Opinion
  • Tags
  • Regional
    • Africa
    • Australia
    • Cambodia
    • China
    • CNMI
    • Europe
    • Hong Kong
    • India
    • Japan
    • Laos
    • Latin America
    • Malaysia
    • Macau
    • Nepal
    • New Zealand
    • North America
    • North Korea
    • Philippines
    • Russia
    • Singapore
    • South Korea
    • Sri Lanka
    • Thailand
    • Vietnam
  • Events
  • Contributors
  • SUBSCRIBE FREE
  • 中文
No Result
View All Result
IAG
No Result
View All Result

S&P Global: Melco unlikely to see leverage, EBITDA margin improvement this year but commitment to debt reduction promising

Ben Blaschke by Ben Blaschke
Tue 18 Aug 2026 at 16:13
Two to Tango

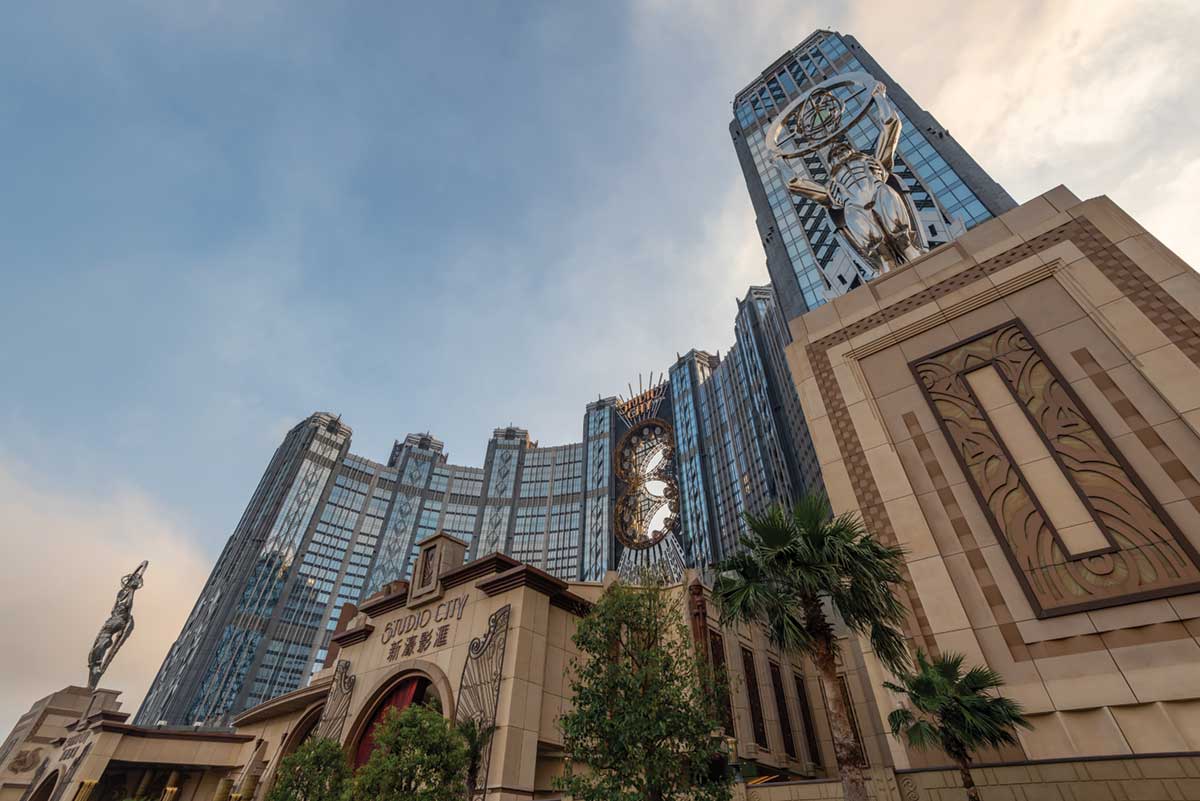
Studio City, Macau

20
SHARES
504
VIEWS
Print Friendly, PDF & Email

Intensified competition among Macau’s concessionaires and the high marketing and commission expenses it demands will likely keep Melco Resorts & Entertainment’s Adjusted EBITDA margin flat through the remainder of 2026, according to latest commentary from S&P Global Ratings.

However, strong cash flow and the company’s commitment to pay down debt should show positive results from early 2027 support both margin and leverage improvement.

In a Tuesday note following release last week of Melco’s 2Q26 earnings, S&P said it expects Melco’s Adjusted EBITDA margin to stay flat at 24.3% in 2026, while its debt-to-EBITDA ratio likely won’t improve to 4.0x – from 5.2x at the end-June 2026 – until the first half of 2027, rather than the end of 2026 as the ratings agency previously anticipated.

This is in part because the Q2 results were negatively impacted by low VIP hold and a reduced gaming volumes thanks to the football World Cup.

“Nevertheless, we expect demand normalization and better operating leverage to support a recovery of Melco’s EBITDA margin in the next six months. This, together with stronger performance in Cyprus and Sri Lanka, should drive EBITDA growth,” S&P said.

The ratings agency also highlighted comments from Melco management during its Q2 earnings call suggesting its focus in the short-term remains the reduction of debt.

“We believe Melco will continue to grow discretionary cash flow and pay down debt over the next 12 months,” S&P said. “The company’s decision to rein in capital expenditure and defer dividend resumption to 2027, alongside the use of trademark sale proceeds to partially pay down debt at Melco International Development Ltd (Melco’s parent) underscores the group’s commitment to debt reduction, in our opinion.”


RelatedPosts

MGM officially launches “Oktoberfest Macau at MGM 2026″

MGM officially launches “Oktoberfest Macau at MGM 2026″

Wed 28 Oct 2026 at 18:17
10 Years Ago – French revelation

Sands China to raise US$1 billion through new senior notes offering

Wed 28 Oct 2026 at 07:19
Macau GGR down 1.2% year-on-year to MOP$18.1 billion in September

CreditSights: Still too early to deem Macau gaming softness as structural

Tue 27 Oct 2026 at 15:56
Gaming credit law changes to reflect measures banning junkets from accepting player deposits

Sands China proposes new notes issue to refinance US$700 million debt

Tue 27 Oct 2026 at 07:53
Load More
Tags: debtEBITDA marginleverageMacauMelco Resorts & EntertainmentS&P Global Ratings
Share8Share1
Ben Blaschke

Ben Blaschke

A former sports journalist in Sydney, Australia, Ben has been Managing Editor of Inside Asian Gaming since early 2016. He played a leading role in developing and launching IAG Breakfast Briefing in April 2017 and oversees as well as being a key contributor to all of IAG’s editorial pursuits.

Current Issue

Editorial – Unraveling the gambling prohibition paradox

Editorial – Unraveling the gambling prohibition paradox

by Ben Blaschke
Wed 30 Sep 2026 at 19:32

I can’t help but notice the sudden and rapid emergence of the term “channelization” across the Asia-Pacific regulatory gaming space...

Reality check – Osaka looms over Korea’s casino boom

Reality check – Osaka looms over Korea’s casino boom

by Ben Blaschke
Wed 30 Sep 2026 at 19:10

Korea’s foreigner-only casinos are setting record revenue numbers, but they are also acutely aware of dark clouds on the horizon...

IAG EXPO 2026 – Elevating the Discussion

IAG EXPO 2026 – Elevating the Discussion

by Ben Blaschke
Wed 30 Sep 2026 at 18:41

The 2026 IAG EXPO was a week of celebration and intense discussion, with the common theme being that this is...

Loyalty in Numbers

Loyalty in Numbers

by Kelsey Wilhelm
Wed 30 Sep 2026 at 18:08

AI is reshaping how integrated resorts can identify and benefit not only premium customers but also grind mass, breaking the...

Hoiana banner
Aristocrat banner
GLI
Nustar
Solaire
Hann
NWR


IAG

© 2005-2026
Inside Asian Gaming.
All rights reserved.

  • SUBSCRIBE FREE
  • NEWSFEED
  • MAG ARTICLES
  • VIDEO
  • OPINION
  • TAGS
  • REGIONAL
  • EVENTS
  • CONSULTING
  • CONTRIBUTORS
  • MAGAZINES
  • ABOUT
  • CONTACT
  • ADVERTISE
  • 中文

Welcome Back!

Login to your account below

Forgotten Password?

Retrieve your password

Please enter your username or email address to reset your password.

Log In

Add New Playlist

No Result
View All Result
  • 中文
  • Subscribe
  • Newsfeed
  • Mag Articles
  • Video
  • Opinion
  • Tags
  • Regional
  • Events
  • Contributors
  • Magazines
  • Advertise
  • Contact
  • About

© 2005-2026
Inside Asian Gaming.
All rights reserved.

  • 中文
  • English