
Macau concessionaire MGM China reported relatively flat revenues in the three months to 30 June 2026, with total revenue of HK$8.63 billion (US$1.10 billion) representing a 0.5% year-on-year decrease and 1.7% lower than the March quarter.
However, total Adjusted EBITDA fell by 7.4% year-on-year and 5.4% sequentially to HK$2.33 billion (US$297 million) with the company highlighting a margin decline from 27.1% in 2Q25 to 23.3% in 2Q26. This, Inside Asian Gaming understands, was directly attributable to a US$21 million increase in intercompany branding license fee expense compared to the prior year quarter after parent company MGM Resorts last year doubled the fee it charges to MGM China for use of the MGM name.
Property EBITDA margin without the brand fee was around 27% in Q2, according to information provided to IAG.
Despite this, the company saw its Macau market share grow from 15.4% a year earlier to 16.4% in 2Q26, continuing the significant growth the company has enjoyed post-COVID.
In its 2Q26 earnings call, MGM noted that volumes were strong through April and May and had rebounded strongly in recent weeks after being clearly impacted by the World Cup in June and early July.
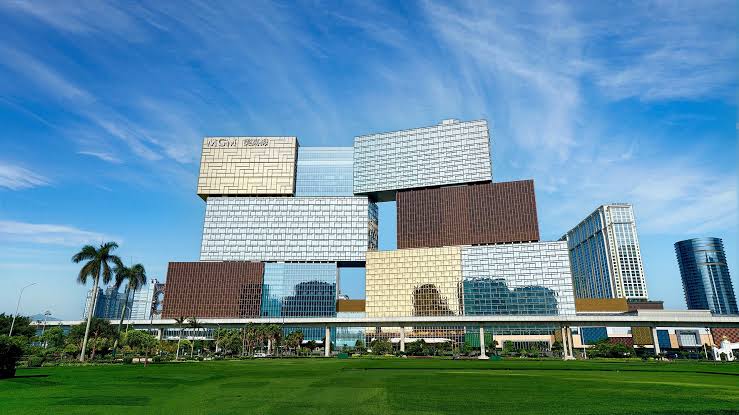
MGM China operates two integrated resorts in Macau, MGM COTAI and MGM MACAU, with both reporting flat revenues in the June quarter.
At MGM COTAI, total revenue of HK$5.28 billion (US$673 million) was in line with the same period last year, while Adjusted EBITDA was down 2.3% to HK$1.50 billion (US$191 million). This was on the back of stable mass table games drop of HK$17.1 billion (US$2.18 billion) and a strong 15.3% increase in slot handle to HK$10.2 billion (US$1.30 billion), although VIP table games turnover dropped by 29.8% to HK$23.0 billion (US$2.93 billion) with a lower win percentage of 2.8% versus 3.5% in 2Q25.
At MGM MACAU, total revenue fell 1.0% year-on-year to HK$3.35 billion (US$427 million) with Adjusted EBITDA of HK$826 million (US$105 million), down 15.4%. Unlike its Cotai counterpart, the peninsula property enjoyed a 51.9% increase in VIP turnover to HK$8.20 billion (US$1.05 billion) with win rate of 2.8% only slightly lower than the 2.9% recorded a year earlier. However, mass table drop declined by 14.0% to HK$12.8 billion (US$1.63 billion). Slot handle was up 7.9% to HK$7.96 billion (US$1.01 billion).
Group-wide, parent company MGM Resorts reported a 1% year-on-year increase in consolidated revenue to US$4.5 billion on strong US regional and Las Vegas performance. Net income attributable to MGM Resorts was US$292 million compared to US$49 million in 2Q25, while consolidated Adjusted EBITDA of US$610 million was down from US$648 million.