


Seaport Research Partners said in a Thursday note that it has marginally adjusted downwards the price targets for most gaming stocks, citing slower growth in Macau and Las Vegas.
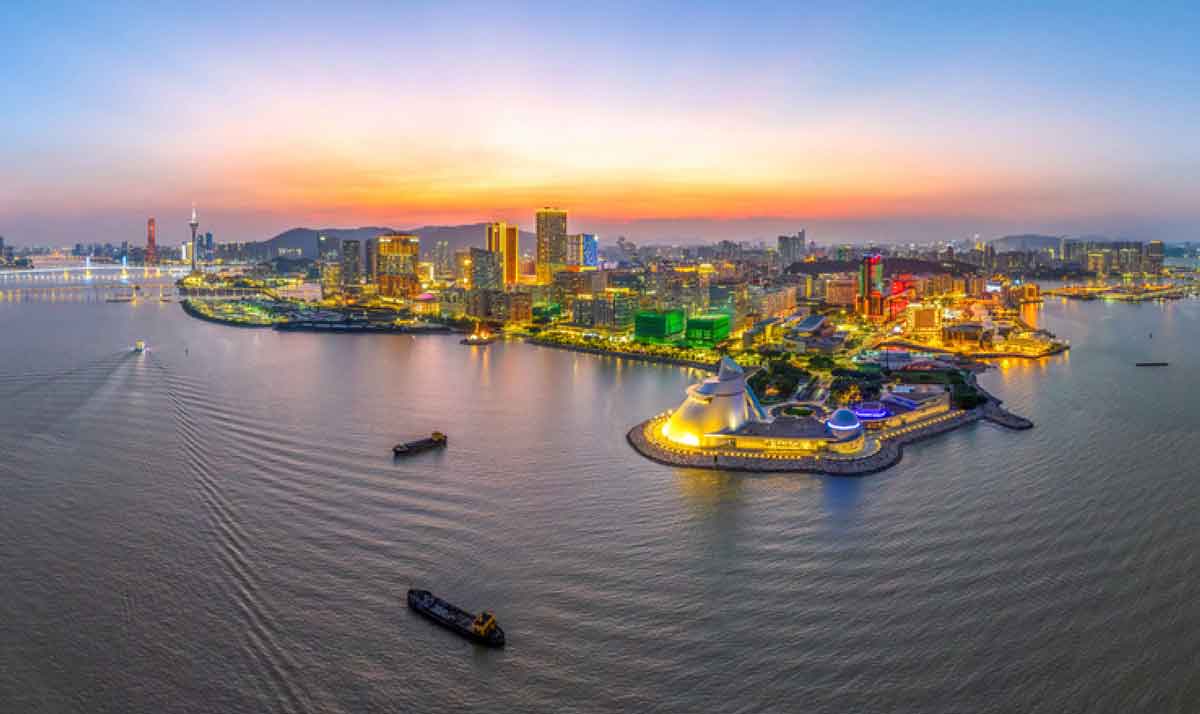
However, Macau-facing stocks continue to present strong risk-reward for investors after “over-correcting” during a brief slowing of momentum in September, according to senior analyst Vitaly Umansky.
With 4Q25 results season just around the corner, Umansky stated Thursday that there should be few surprises for the quarter, with revenue likely to have grown by more than 13% year-on-year and EBITDA by over 15% – benefiting from high VIP hold.
Higher hold now appears structural, he added, although Q4 margins were seemingly suppressed on higher expenses related to special events and player reinvestment in the premium mass segment.
Seaport has adjusted downward the target prices for almost all operators under coverage – with the exception of Galaxy Entertainment Group – including Las Vegas Sands, MGM Resorts, Melco Resorts, Wynn Resorts, MGM China, Sands China, SJM Holdings and Wynn Macau.
But although Las Vegas specifically remains a headwind for MGM and Wynn in-particular, Umansky stated, “We believe stocks have over corrected since August and, while there are Macau specific and China macro risks (along with geopolitical risks), gaming stock valuations (in particular those with Macau exposure) remain largely too low, resulting in a strong risk/reward positioning.”
With Macau names still trading at a 28% discount to pre-COVID EV/EBITDA, he added, “At current valuation levels, we believe investors are being well compensated to take on China-related risk (in most of our coverage universe).”
Las Vegas Sands and Wynn Resorts remain top picks for Seaport, the former on Marina Bay Sands’ strong performance and the latter on the planned 2027 launch of Wynn Al Marjan Island in the UAE.
RelatedPosts